Airtel Money

Contributor Image
Written By
Contributor Image
Written By
William Berg
William Berg is a legal expert with a focus on securities law and a long track record in the trading industry.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Updated

Airtel Money is a mobile money service that allows customers to store funds, send and receive payments, pay merchants, and access certain other financial services through a mobile phone. For online traders in several African markets, Airtel Money can provide a practical way to make small-scale deposits and withdrawals to and from an online broker trading account, avoiding the need to fund every transaction through a conventional bank card or bank transfer.

Airtel Money is an electronic wallet linked to a registered mobile number. A customer can add money through authorised agents and other supported channels, then use the wallet for person-to-person transfers, merchant payments, bills, and other financial services, including transfers to and from brokerage accounts. Airtel Africa describes its agent network as a central part of the system, providing locations where customers can load funds onto their phones and convert electronic money back into physical cash.

At the time of writing, Airtel Africa operates across 14 African markets, although the services and payment integrations available to traders vary considerably from one country to another. For the 2025/2026 financial year, Airtel Africa reportedly had over 54 million Airtel Money customers, approximately 2.4 million active agents, and $196 billion in transaction value. Airtel Money is one of several mobile money solutions that have grown large in Africa, alongside mobile-money service providers such as M-Pesa (especially in Kenya), MTN MoMo (especially in Ghana), and Orange Money (especially in in Francophone Africa).

In this guide, we will look at Airtel Money from the perspective of a swing trader in Africa using online brokers. The guide explains how deposits and withdrawals work with Airtel Money, account security, costs, how to pick a suitable broker that accepts Airtel Money, and more.

Airtel Money can be a convenient route for local deposits and withdrawals method for swing traders in African markets where brokers have integrated the wallet. The payment method itself does not improve a trading strategy, but quick local deposits and withdrawals can make account management easier, especially for traders who already receive income and make everyday payments through mobile money.

However, picking a broker simply because it accepts Airtel Money is not the best course of action. The better approach is to choose a properly regulated broker, where the trading platform and the markets available for swing trading suits your preference. Naturally, comparing costs (including things such as spreads, overnight fees, and transaction fees) is also important, as this can vary a lot between brokers.

For retail brokerage companies, this creates an obvious reason to support local mobile money such as Airtel Money and M-Pesa. A trader who already receives wages or business income through a mobile wallet may find a card-only broker unnecessarily difficult to fund, and for many small-scale swing traders, the costs associated with conventional bank transfers would quickly erode profits. Broker integrations with Airtel Money and similar affordable mobile-money services lower the payment barrier between local financial activity and international speculative markets such as forex, commodities, and global equity indices.

With that said, lower payment barriers do not reduce investment risk. In some ways they make disciplined risk management even more important because a trader can move money from an everyday wallet into a leveraged account very quick and with relatively little friction. Mobile money improves financial access while also making it easier to fund a losing trading account in the heat of the moment, and those two effects need to be considered together.

How Airtel Money Works

Airtel Money is an electronic wallet linked to a registered mobile number. A customer can add money through authorised agents and other supported channels, then use the wallet for person-to-person transfers, merchant payments, bills, and certain other financial services. Airtel Africa describes its agent network as a central part of the system, providing locations where customers can load funds onto their phones and convert electronic money back into physical cash.

For a trader, an essential part is of course the connection between the wallet and the broker’s payment processor. If Airtel Money is available for the trader’s account, the trader selects it from the broker’s funding page, enters an amount, and confirms the payment through the registered phone. The trading platform then credits the account after receiving confirmation that the mobile transaction was successful.

The process is similar to using other mobile money services, but Airtel Money and M-Pesa should not be treated as interchangeable. A broker may support both in one country, only one in another, and neither in a third country. Availability can also depend on account currency and the legal broker entity serving the customer, so seeing an Airtel Money logo on a broker’s global site does not prove that the method will appear in every customer’s funding page.

Funding an Airtel Money Wallet

Airtel Money customers can normally add funds through the operator’s agent network and other supported financial channels. Airtel Africa reports approximately 2.4 million active Airtel Money agents across its mobile-money footprint as of the 2025/26 financial year. Agents provide the cash-in and cash-out infrastructure that makes mobile wallets practical even for customers who do not rely heavily on conventional bank accounts and need to be able to convert physical money into digital money and back.

As a trader, make sure the mobile wallet and the phone are registered in exactly the same legal name used for your brokerage account. Discrepancies can cause payment problems, because brokers need to establish where customer funds came from, and names that do not match up can trigger anti-fraud protocols.

Only use your own phone and mobile money wallet. Borrowing another person’s phone and Airtel Money wallet for a deposit can seem harmless, and you might even be able to make a successful deposit. But it is not unusual for withdrawal requests to receive more scrutiny than deposits, and a successful deposit is never a guarantee that the withdrawal will smooth as well.

Where is Airtel Money Used in Africa?

Airtel Money is not exclusively an African service, but Africa is by far its most important market today. At the time of writing, Airtel Africa operates across 14 African markets, although the services and payment integrations vary considerably from one country to another. Airtel Money forms part of a broader move from cash transactions toward digital financial services in African consumer and small business markets.

Airtel Africa states that it had 54.1 million Airtel Money customers as of 31 March 2026, an increase of 21.3% from the previous year, while its agent network reached about 2.4 million. The service is used for merchant payments, transfers, bills, and other financial products.

The most significant markets for Airtel Africa are currently Tanzania, Kenya, Uganda, Zambia, Malawi, Rwanda, and the Democratic Republic of the Congo (commonly known as DRC / Congo-Kinshasa). The minor markets are Nigeria, Niger, Chad, Gabon, Congo-Brazzaville, Madagascar, and the Seychelles.

Tanzania is one of Airtel Money’s most important markets, and the payment service has a long-established and substantial presence in this country. Tanzania is also a country where mobile money in general is widely known and utilized for everyday financial activities. Tanzania is a highly developed mobile-money market, with several competing wallets rather than a single dominant provider.

Kenya is an extremely important mobile-money market, but Airtel is a challenger here, and not the dominant player. Airtel has a significant and growing telecom and mobile-money presence in Kenya, but it competes against the exceptionally strong M-Pesa ecosystem. Airtel has been investing heavily in its distribution network in Kenya in recent years, and the Airtel Money agent network in Kenya increased by 77.9% in 2024/2025.

Airtel is one of Uganda´s major telecommunications operators, and Airtel Money is a well-established part of it´s financial-services business. The service is used for transfers, merchant payments, bills, airtime and other everyday transactions, and there is a large agent/distribution network available.

How to Deposit and Withdraw With an Airtel Money Broker

Depositing into your trading account using Airtel Money

The trader normally begins inside the broker’s secure client portal. Airtel Money is selected from the available payment methods and the deposit amount is entered. Depending on the country and payment processor, the broker may request the registered telephone number, local currency, or another payment detail before initiating the transaction.

A payment prompt or authorisation request is then sent to the phone. The trader should check the amount and exact recipient before entering the Airtel Money PIN. After successful authorisation, a confirmation or transaction reference should be retained.

Check if the money is now visible in the broker account. If the Airtel wallet has already been debited but the trading balance has not updated after some time, contact the broker’s payments team. With the confirmation your saved, you can provide the amount, time, registered number, and transaction reference needed to trace the first transfer.

Withdrawing from your trading account using Airtel Money

Where withdrawals to Airtel Money are supported, the request normally begins inside the broker’s secure client portal. Brokers commonly require money to return through the same payment route used for the original deposit because this helps satisfy payment-security and legal requirements (including mandatory anti-money-laundering and anti-fraud controls). Make sure you keep you Airtel Money wallet active while the trading account is in use, even if you do not plan on making any withdrawal soon.

A swing trader using leverage should always check free margin before requesting a withdrawal. Suppose the account contains $2,000 but $1,400 is supporting open leveraged positions. Removing $1,000 simply because the cash balance appears large will dramatically weaken the margin level. A moderate adverse movement may then cause positions to be closed automatically.

Airtel Money Transaction Times for Traders

Deposits

Airtel Money deposits can be credited rapidly when the broker and payment processor support automated mobile-money transactions. Two examples are FXPesa and Scope Markets, who both describes their supported Airtel Money deposits as instant. In this context, “instant” should still be understood as the normal processing target rather than a guarantee that every payment will appear immediately. Delays can occur because of issues such as mobile network problems, payment-gateway maintenance, or broker compliance checks. A mismatch between the name on the Airtel wallet and the name on the trading account can trigger manual review. The same can happen where a trader suddenly deposits a much larger amount than normally or attempts several transactions in quick succession.

Withdrawals

Withdrawal requests from a trading account often take longer to process than deposits because the broker may review the request before releasing the money, to ensure it complies with internal and external security requirements. This is not unique to Airtel Money withdrawals. Also, traders should distinguish between broker approval time and Airtel Money transfer time. A mobile transfer may be rapid after approval even if it was stuck with the broker for several hours before that, pending a manual review.

FXPesa states that withdrawal requests received before its stated business-day cut-off may be processed the same day, but that first withdrawals can require additional checking.

Airtel Money Fees and Currency Conversion

Airtel Fees

Airtel Money does not have one universal fee structure across Africa. Charges depend on factors such as country/market, transaction amount, transaction type, and whether the transfer is on-network or to another network.

Broker fees

The broker can impose its own transaction processing fee or choose to absorb it. FXPesa currently advertises no broker fee for the Airtel Money routes displayed in its funding table, while Scope Markets states that it does not charge a separate fee on its supported Airtel Money route but that ordinary Airtel Money charges can still apply.

Currency conversion costs

Currency conversion can cost more than the visible payment charge. A trader may for instance send KES, UGX or TZS while maintaining a USD trading account. Somewhere in the payment process the local currency needs to be converted. The rate offered can contain a margin above the underlying foreign-exchange rate, meaning a deposit advertised as fee-free still has a measurable cost. Understanding this is particularly important for swing traders who frequently withdraw profits and then redeposit. Converting from local currency to USD, then back to local currency, then to USD again, and so on, creates repeated foreign-exchange costs. A trader who keeps capital in the brokerage account for several trading cycles incur fewer conversion costs than somebody who moves the same funds back and forth.

Picking a Broker That Accepts Airtel Money

A swing trader should choose a broker based on more than its ability to accept Airtel Money. Mobile funding solves only the movement of cash into and out of the account. The trader also needs to consider factors such as available markets, trading costs, reliable execution, and a suitable regulatory situation. Overnight financing (swap/rollover fees) becomes especially important for swing traders, because some positions may be held open for weeks.

Regulation

Payment convenience should never replace broker verification. A company accepting Airtel Money is not necessarily reputable and properly regulated simply because the payment method is familiar. Traders should identify the exact legal entity holding the account and verify it with the regulator responsible for that jurisdiction. In Kenya, the Capital Markets Authority maintains a public database of licensed financial companies, including non-dealing online forex brokers.

This matters because recognised broker brands can operate several legal entities in different countries, with the various companies typically belonging to the same company group but being subject to different jurisdictions. An international company group may for instance include a CMA-regulated Kenyan company, a South African company regulated by the Financial Sector Conduct Authority (FSCA), a British company regulated by the UK Financial Conduct Authority (FCA), and several other companies regulated in countries known to be more permissive when it comes to trader protection, e.g. Belize, Vanuatu, Saint Vincent and the Grenadines, and the Seychelles. The company named in the client agreement determines which regulator and rules govern the account.

Start by verifying the exact legal broker entity and its regulator. Then visit the regulator to verify the broker is actually licensed by them, and holds an active an appropriate license. Do not follow any links provided by the broker. Find the regulator (financial authority) independently and search their registry yourself. Then, if possible, use the website listed in the registry to start the sign-up process.

Trading strategy, instruments, and costs

Check if the instruments or products required for your strategy are available, and compare factors such as spreads, commissions, overnight fees, available leverage, and stop-out rules.

It is the cost of using your particular strategy that matters. For a swing trader, swap rates can be more important than a tiny difference in the advertised spread. Saving one fraction of a pip at entry means little if a large overnight charge is applied repeatedly during a ten-day position. One of the biggest differences between swing trading and day trading is that swing traders intentionally keep positions open overnight. With leveraged forex and CFDs, this can create financing charges commonly described as swaps, rollover or overnight financing. The exact calculation depends on factors such as instrument, position size, direction of the position, and the number of nights it remains open. A strategy that looks profitable before financing can become much weaker after several days of holding costs. Suppose a trader expects a position to make 1.5% over ten days but pays meaningful overnight charges during that period. The cost is part of the trade and should be included before entry rather than treated as an administrative detail discovered after the position closes. Some instruments can generate positive swap in one direction and negative swap in the other because of interest-rate differences, while others charge financing regardless of the direction. Brokers may also apply a larger rollover on one day of the week to account for weekend settlement. A swing trader should therefore check the contract specification rather than assuming that each night has exactly the same cost.

Platform

Platform also matters. Swing traders often need dependable charting for particular time frames, pending orders, more than one type of stop-loss order, phone alerts, and enough historical data to analyse medium-term market structure. MetaTrader 4 and MetaTrader 5 are common among African forex brokers, while some providers also offer proprietary platforms. The best platform is not necessarily the one with the most indicators for technical analysis, it is the one that allows the trader to execute the planned strategy consistently.

Airtel Money Transfers

The Airtel Money section should be checked for supported markets, currencies, minimum and maximum transactions, withdrawal rules, and any fees charged by either the broker or Airtel Money.

Are traders in your country allowed to use Airtel Money for both deposits and withdrawals with this broker? Access to Airtel Money instant depositing becomes less appealing if withdrawals require an expensive alternative method, e.g. international bank transfer. The complete trading and payment cycle should be considered rather than just one attractive number.

Airtel Money and Margin Management

Mobile money, such as Airtel, can make adding funds to a trading account a quick and easy process. This can both beneficial and dangerous at the same time.

There is a big difference between planned funding and emergency funding/emotional funding. A trader who sticks to a trading plan can use Airtel Money as an ordinary funding tool, in accordance with the monthly trading plan. A trader who acts ad-hoc and repeatedly deposits after losses because positions are approaching a margin close-out is behaving very differently.

  • Planned deposit: “I am adding additional capital for planned trades I’ve already budgeted for.”
  • Emergency deposit: “My trades are losing, so I’m frantically adding money to prevent them from being closed.”

Adding funds to save a losing position does not reduce the market loss. It increases the amount of capital exposed to the same trade. There can be legitimate reasons to increase margin, but the decision should be part of the trading plan. If every adverse movement is followed by another mobile deposit, the wallet has effectively become an extension of the leveraged trading account.

Swing traders can reduce this risk and help maintain discipline by deciding in advance how much money will be allocated to the brokerage account before the trading period begins. If the account reaches a predetermined loss threshold, trading should stop for review rather than immediately drawing another amount from Airtel Money. Convenient payments should make account administration easier, not make loss chasing faster.

The main advantage with Airtel Money is convenience. Fast and easy deposits can be useful before a planned trading week. But a swing trader should not depend on emergency mobile deposits to rescue positions that have moved too far against the original analysis. If the account repeatedly requires fresh money to avoid margin close-outs, the position sizing problem needs to be addressed before the payment method.

The convenience of mobile money creates a behavioural risk that deserves to be taken seriously. If a position loses heavily, a trader can potentially add another deposit from a phone within minutes. This is much easier than visiting a bank office or waiting for a conventional international transfer to go through, and that convenience can become dangerous when the decision is made under pressure.

A swing trader should decide account funding before the trade rather than after it. If $500 has been allocated to a trading strategy, losing $200 should not automatically trigger another $200 Airtel Money transfer. The trader should first establish why the original loss occurred and whether further trading still fits the plan.

Airtel Money Security for Traders

Airtel Money uses account and transaction authentication, but the trader still needs to protect both the wallet and brokerage account. A mobile-money PIN should never be provided to anyone else, including some who is (or is claiming to be) a broker representative, a signal seller, or supposed support employee (Airtel or Brokerage Company. The mere fact that this person is asking for your Airtel Money PIN is a big red flag. A genuine support process may require a transaction reference and identity verification, but another person does not need the customer’s secret PIN to trace a payment.

Unexpected payment prompts are another warning sign. A scammer can impersonate a broker representative and claim that a withdrawal or deposit needs to be confirmed. The customer should only approve a transaction that they initiated and should check the amount and recipient first. A request that appears without an active deposit attempt should be rejected. Do not approve a request simply because the message contains the name of a familiar payment service.

The trading account needs separate protection. A strong password and two-factor authentication should be used where available. Protecting Airtel Money does little good if an attacker can sign into the broker, change account information, or interfere with withdrawal requests. Traders should also protect the email account connected to the broker because email access can sometimes be used to reset trading-account credentials.

The phone (and computer, if applicable) also need to be protected. Keep your phone locked and do not lend it to others if it is used for money management (e.g. Airtel Money) and online trading. Do not allow anyone to get remote access to your device. Deny all requests for screen-sharing. This is true even if you are talking to customer support staff (or alleged customer support staff).

Fraudsters can be very pushy and try to create a situation where you feel very stressed. They want you do act quickly. They do not want you to have time to verify their story independently by actually contacting the relevant entity (broker, Airtel, your bank, police office, etc) through the official channels. They also don´t want you to have time to discuss the matter with a trusted friend, family member, or colleague who might be familiar with this type of scam and recognize the warning signals. Do not fall for manufactured stress.

Pros and Cons of Airtel Money Brokers for Swing Traders

Pros of Airtel Money for Swing Traders

  • Mobile funding can be quick and convenient in countries where Airtel Money is widely used, reducing reliance on cards and international bank transfers.
  • Local-currency payment routes such as Airtel Money can be practical for traders who receive their income in KES, UGX, TZS, or another supported currency.
  • Airtel’s large agent infrastructure in parts of Africa gives customers in these regions a convenient route between physical cash and electronic trading-account funding.
  • Some regulated brokers support both deposits and withdrawals through Airtel Money, allowing traders to return money to the wallet used for funding.

The most useful advantages are practical rather than strategic. Airtel Money can reduce payment friction, but it cannot improve an entry signal or turn an unprofitable swing strategy into a profitable one. Traders should judge the broker primarily on regulation, execution, instruments, costs and overnight trading conditions before treating mobile funding as a deciding factor.

Cons of Airtel Money for Swing Traders

  • Airtel Money availability is country-specific and can differ even within the same brokerage company group and brand.
  • Wallet and transaction limits may make the method inconvenient for larger trading accounts.
  • Some brokers only allow Airtel Money deposits.
  • Currency conversion can add costs where the wallet and brokerage account use different currencies. (This downside is not unique to Airtel.)
  • Fast funding can encourage impulsive deposits after losses or when an account is close to a margin call. (This downside is true for all fast-funding methods.)
  • A broker can change payment processors or remove an Airtel Money route. Traders should maintain another practical withdrawal option.

A trader should also remember that mobile-money acceptance says almost nothing about the quality of the trading conditions. A weak broker can offer a convenient payment method and a strong broker can have a less convenient cashier. The funding method should therefore be considered after the broker has passed the other checks, e.g. regulatory check and trading-cost check.

FAQ

What is an Airtel Money broker?

When we say Airtel Money broker, we do not mean a broker owned by Airtel Africa plc or the Bharti group of India. We means a broker that supports Airtel Money as a deposit method (or deposit and withdrawal method) for at least some customers. Depending on the circumstances, it may be possible to make deposits, withdrawals or both through the mobile wallet. Availability normally depends on the customer’s country, broker entity, and account currency, so support should be checked inside the broker’s current funding section rather than assumed from general reviews or based on Airtel logos on the main broker website.

Is Airtel Money good for swing traders in Africa?

Airtel Money can be a practical payment method for swing traders in supported markets in Africa. The main advantages are security, convenient local funding, and potentially fast withdrawals.

Which brokers accept Airtel Money?

Current examples include FXPesa, which lists Airtel Money across several East African mobile-money routes, IC Markets Kenya, whose product documentation includes Airtel Money among supported country-specific mobile payments, and Scope Markets, which currently documents Airtel Money for eligible Uganda clients. Availability can change, so these examples should be checked directly before a deposit is made.

Can I deposit KES with Airtel Money?

Yes, where the broker supports a Kenyan Airtel Money route. FXPesa currently lists Airtel Money among its KES mobile-money deposit and withdrawal methods. Another broker may accept Airtel Money only in Uganda or Tanzania, so Kenyan support needs to be verified for the individual account rather than inferred from the presence of Airtel Money elsewhere on the broker’s website.

Can I withdraw swing trading profits to Airtel Money?

Yes, if the broker’s Airtel Money integration supports withdrawals in the customer’s country. Brokers often prefer withdrawals to return through the same method used for deposits. Account verification must normally be complete, and the wallet should be registered in the trader’s own name.

Are Airtel Money deposits instant?

They can be. Some brokers currently describe supported Airtel Money deposits as instant, but factors such as technical problems, network outages, and compliance reviews can cause delays.

Does Airtel Money make a broker safe?

No. Airtel Money is a payment service, not a guarantee that the broker is properly regulated and trustworthy. Traders should verify the brokerage company with the relevant financial regulator independently. A familiar mobile wallet should never substitute for evaluating the brokerage company.

Should swing traders keep all their money at the broker?

The account needs enough capital to support planned positions and normal fluctuations without operating constantly near a margin close-out. Capital that is not required for the strategy can be kept elsewhere according to the trader’s own financial plan. Mobile-money withdrawals can make moving smaller amounts convenient, but repeated withdrawals and redeposits may create substantial transaction and currency conversion costs.

Can Airtel Money help during a margin call?

A fast deposit may increase available margin if it reaches the broker in time, but relying on emergency deposits is poor risk planning. Network or payment delays can occur precisely when the trader wants immediate funding. More importantly, adding money does not repair an unsuccessful trade. Swing traders should normally size positions so ordinary market movements can be absorbed without depending on another mobile-money transfer, and there should also be a stop-loss in place.

Before signing up with any broker, make sure you know if your retail account has statutory negative balance protection (NBP), contractual NBP, or no NBP, and what this entails.

About Airtel and Airtel Money

Airtel

The central company is Bharti Airtel Limited, a publicly listed Indian telecommunications group. It is the flagship company of Bharti Enterprises, founded by Sunil Bharti Mittal. Bharti Airtel operates in India and has African operations through its ownership of Airtel Africa.

At 31 March 2025, Bharti Airtel’s largest shareholder was Bharti Telecom Limited, with 40.47% of Bharti Airtel. Bharti Telecom is part of the promoter structure associated with the Bharti/Mittal group. Bharti Airtel itself was 52.42% promoter/promoter-group owned at that date. 

The story starts with Bharti Enterprises, founded by Sunil Bharti Mittal in Indian in 1976. It was initially a diversified entrepreneurial group, not a telecom company. Airtel

Bharti subsequently moved into telecommunications, and Bharti Telecom Limited was incorporated in 1985. Bharti Telecom is controlled by the Bharti family, ultimately through Bharti Enterprises (Holding) Private Limited and family trusts.

Airtel Money

Airtel Money is ultimately controlled by the Bharti group of India, through Bharti Airtel and its African subsidiary Airtel Africa plc. As of June 2026, Bharti Airtel increased its effective ownership of Airtel Africa to about 79.22%, giving it clear control. The ultimate controlling entity is Bharti Enterprises (Holding) Private Limited, which is controlled by trusts associated with the Bharti family, including the family of Sunil Bharti Mittal. 

The ownership structure is roughly:

  • Bharti Enterprises / Bharti family
  • Bharti Airtel Limited (India)
  • Airtel Africa plc
  • Airtel Mobile Commerce B.V. (AMC BV)
  • Airtel Money operations across Africa

Airtel Africa’s 2026 annual report identifies Airtel Mobile Commerce B.V. (AMC BV) as the holding company for Airtel Africa’s mobile-money operations outside Nigeria. Airtel Mobile Commerce B.V. (AMC BV) is the holding company for Airtel Africa’s mobile-money operations except the Nigerian payment service bank (PSB) operations. For Nigeria, the key entity is Airtel Mobile Commerce Nigeria Limited (AMCN), which operates Airtel Money in Nigeria.

Airtel Money itself isn’t simply one company operating identically in every African country. The wallet services are operated through local companies and subject to national law, which matters when you’re looking at things such as forex broker transfers, fees, licensing, and whether Airtel Money can fund a particular broker in your country.
Event Options & Prediction Markets

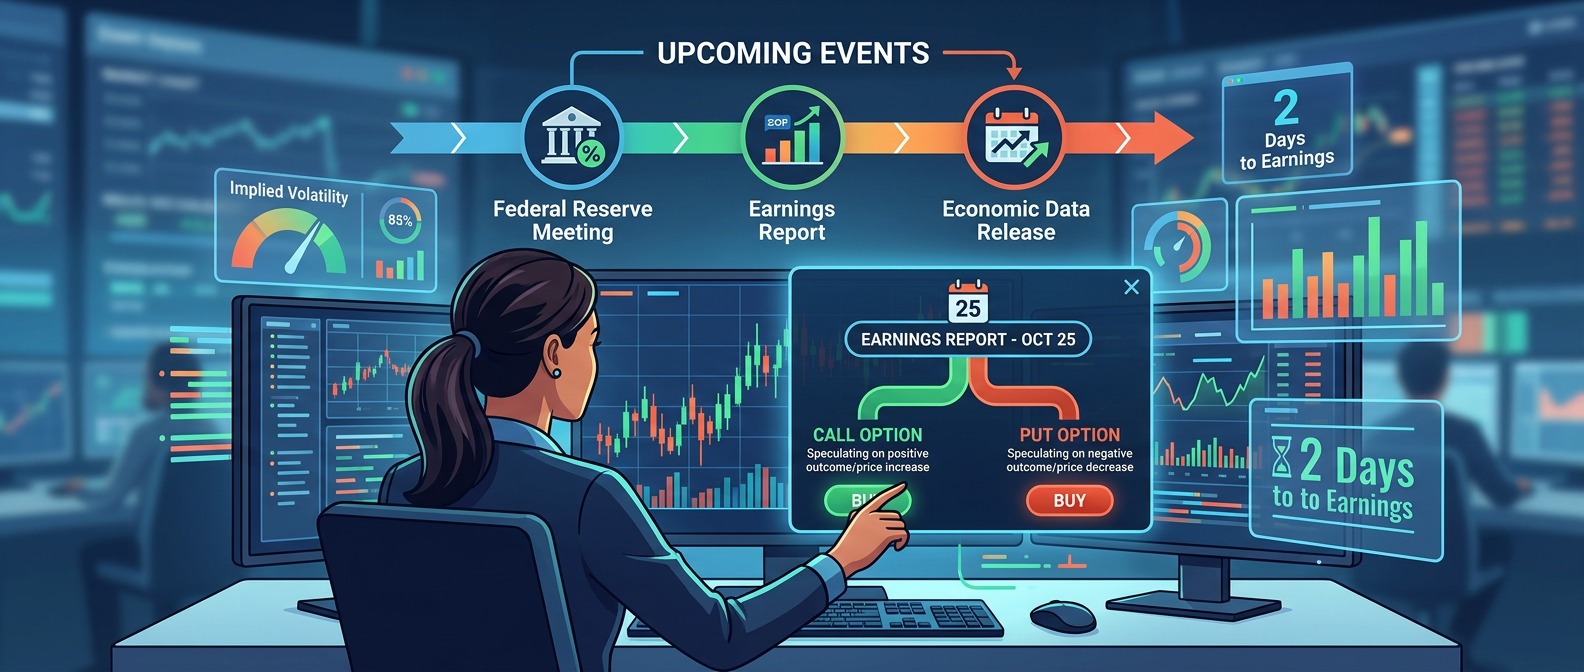
“Event markets” is a category of trading venues where contracts settle based on whether a specified real-world event occurs. These contracts look a lot like binary options, since the eventual payoff depends on an external, verifiable outcome rather than the price path of a continuously traded asset. In many ways, they are also similar (or identical) to sports betting, and it is not surprising that regulators, courts, and authorities in the United States are currently struggling to clarify exactly how event markets should be treated from a legal point of view.

Before we go into the nitty-gritty of event market regulation, however, we will begin at the beginning, and look at how event market trading works and how it is both similar and different from other types of trading. Continue reading if you want to learn more about the mechanics of how these contracts are listed and traded in the United States, the arithmetic that determines profit and loss, how platforms structure payouts and margin, how the pricing should be read, and how market makers and arbitrageurs operate.

We will then look into the enforcement framework that matters for traders in the U.S. and why federal and state regulators, including the Commodity Futures Trading Commission (CFTC), are in conflict over these instruments. To understand the field better, we need to study both relevant litigation, state enforcement actions, and the policy objections that motivate the various viewpoints.

event options

What are event markets?

An event market is a venue that lists one or more event contracts. An event contract ties a financial payoff to a discrete question: Does X happen by time T? The defining attribute is that settlement depends on the resolution of a clearly specified external fact rather than the gradually shifting price of a continuously tradable asset.

Event contracts are commonly structured as binary, cash-settled instruments. The typical retail framing is simple: a contract pays $1 if “Yes” occurs and $0 if “No” occurs. That design makes the contract equivalent, in payoff terms, to a binary option with a fixed terminal payoff and a clearly bounded loss for the buyer. That payoff template is why many exchanges and retail platforms refer to these instruments as “prediction contracts” or “event options”. Institutional descriptions use the neutral term “event contract” or “information contract”.

Practical implementations vary by platform and jurisdiction, but the core template is consistent. Price ranges from zero to one in decimal terms, and that price can be read as an implied probability under frictionless assumptions.

Event contracts fall into at least three useful buckets for traders and regulators, and each bucket has different counterparty risk, manipulability, and regulatory exposure.

  • Objective operational events. Examples: “US CPI released on YYYY-MM-DD is above X.” These are easy to define, resolve, and monitor.
  • Sports and entertainment events. Examples: “Team A wins the championship.” These are high-volume retail events, but from a legal and political perspective, they create state gaming friction.
  • Political and governance events. Examples: “Will X party control Congress after Election Y?” These create the strongest policy objections and the most litigation risk.

Product mechanics

Contract details

A normal event contract will specify four things clearly: the event definition (what exactly constitutes “Yes”), the resolution source (which authority or data feed determines the official outcome), the resolution time (the exact clock time or event milestone that closes the market), and settlement rules (how the cash payoff is determined and when it will be paid). Platforms typically publish both contract specifications and an appeals process for contested outcomes.

That sounds obvious until you read disputes. Ambiguities can for instance arise from partial events (a game suspended then finished later), retroactive data revisions (an agency corrects a statistic after publication), or meta-questions (what does “control Congress” mean in the face of contested seats?). Quality platforms anticipate these problems by naming a primary source (such as an official league statement, an agency release, or a designated count of certified returns) and by describing fallback procedures. The fallback and appeals process is a real product risk. Example: If you trade on an event where the resolution source can be changed or reinterpreted later, you are taking resolution risk in addition to directional risk. The single biggest source of dispute is imprecise wording. Contracts that use undefined terms or ambiguity invite litigation. For example, “Will Candidate X concede” is harder to define than “Will Candidate X be certified as the winner by the state election authority by date T?” The latter is resolvable by referencing a named document and a date; the former is subjective. Precision matters for both trading and compliance.

Pricing as implied probability: intuition and caveats

The standard retail short-hand interpretation is that a contract priced at $0.62 implies a 62% probability of the event occurring. That interpretation is correct under frictionless market assumptions. If the market is deep and arbitrageurs can trade freely, the marginal price equates to consensus probability. Traders use that mapping extensively and that is why event markets are often discussed as forecasting tools.

But the mapping breaks down where frictions exist. Position limits, low liquidity, asymmetric participation, fees, and transaction costs all distort the price-as-probability reading. A $0.62 price in a tiny market with a wide spread and low volume is not the same information as $0.62 for a thick, continuously traded contract. Platforms with thin depth can be pushed, and pricing may reflect the willingness of a small set of counterparties to take risk rather than an objective probability.

The binary payoff simplifies the arithmetic. For a buyer of a “Yes” contract purchased at price p, the payoff at settlement is either $1 (if Yes) or $0 (if No). Profit equals (1 − p) if “Yes” occurs and (0 − p) if “No” occurs, before fees. That boundedness is what makes these instruments feel similar to classic binary options.

Continuous trading and exit options

Most exchange-style event contracts allow buying and selling up to resolution. That transforms the product from a fixed-wager “bet and wait” instrument into a tradable derivative where position management matters. Traders can enter early, scale in as probability shifts, and exit before settlement (if liquidity permits). Continuous trading also creates the conditions for market-making and arbitrage. Platforms that enable continuous trading thereby increase the likelihood that prices reflect aggregated marginal beliefs (under sufficient liquidity and appropriate market design) rather than idiosyncratic wagers. They also introduce typical market microstructure issues, e.g. spread, latency, and market impact.

If we take a closer look, we can see how continuous trading changes the nature of the product, because once you can trade up to resolution, an event contract behave like a tradable derivative rather than a fixed “bet and wait” wager. Position management (entry timing, scaling, hedging, early exit) becomes central. Continuous trading also allows prices to incorporate marginal belief updates over time, rather than being dominated by initial wagers or a small set of early participants. This is one of the classic arguments for prediction markets. If there are multiple related contracts, time decay toward resolution, or cross-venue pricing differences, continuous trading creates room for liquidity provision, calendar arbitrage, cross-market arbitrage, and dynamic hedging.

With continuous trading, you inevitably get spreads, adverse selection, inventory risk, latency advantages, and market impact, exactly as you’d expect from any order-driven or Automated Market Maker (AMM) based market. Once you allow continuous trading, you inherit the same frictions and strategic problems that exist in any real market, even if the underlying payoff is just a simple yes/no outcome.

It is important to remember that continuous trading enables better aggregation, but doesn’t guarantee it. Thin markets can still be dominated by a few informed traders, manipulation attempts, or stale prices that don’t move until someone pays the spread. Examples of factors that can play a major role are fee structure, position limits, and information asymmetries near resolution. Not all participants are belief-driven. Some traders are hedging, some are speculating short-term volatility, and some are liquidity providers. Prices reflect marginal willingness to trade, not a pure belief average.

Settlement and edge cases

Settlement is triggered when the contract’s specified resolution condition is met and the named resolution source issues an outcome, subject to any appeal window. Settlement is normally cash-only: the correct side gets $1 per contract, the incorrect side gets $0. Platforms publish settlement dates and timelines for cash transfers. High-quality venues specify what happens if the primary source is corrected, whether delayed outcomes push settlement to a later date, and how disputes are adjudicated. These rules are substantive financial product details. In litigation, courts and regulators have focused on whether the rulebook offered a reasonable, publicly available process for resolution.

Payouts, fees, collateral and financing: Understanding the economics for traders and platforms

The basic payout arithmetic

Most retail event contracts use a fixed payout model. The buyer’s maximum loss equals the purchase price, and the maximum gain equals one minus the purchase price. If you buy a “Yes” contract at p, at settlement your P/L is:

  • If Yes: + (1 − p) before fees.
  • If No: − p before fees.

Sellers realize the mirror image. That simple math makes position-level risk trivial to compute. Aggregate risk for the platform and for leveraged participants is more complex because of margining, netting, and concentration.

Fees and the “house edge”

Platforms extract value through explicit fees (per-contract fees, commissions), through spread and market-making margins, and through financing or interest on collateral. Two platforms can quote the same mid price but differ materially in economics if one charges higher transaction fees or keeps interest on full collateral while another pays interest or offers margin. As a trader, you should compute the actual effective cost per round trip and per day for carry, instead of relying on the marketing headlines when selecting a platform.

Some venues require full collateral up front, which means that customers must post cash equal to the full potential loss. This makes the product effectively pre-funded and reduces counterparty credit risk on the exchange side. Other venues have sought permission to offer margin, at least to institutional participants. Margin changes both user economics and platform risk. It reduces the capital required to take a position but increases the platform’s exposure to default and creates paths to rapid account liquidation in volatile events. News reporting has highlighted that Kalshi sought to introduce margin trading for institutional users, a change that would make event contracts look more like futures from a funding perspective.

Platform economics and float

Event markets typically require traders to post collateral sufficient to cover their worst-case loss, and that collateral remains with the platform until positions are closed or the event resolves. During this time, the collateral constitutes economic float. Where platforms hold collateral, the treatment of that float matters.

If the platform retains any interest earned on that float without crediting users, traders are effectively providing zero-interest financing to the platform, which functions as an implicit fee even when explicit trading fees are low or absent. Conversely, platforms that credit interest or otherwise rebate funding reduce this source of carry.

In markets with heavy turnover, the aggregate amount of collateral held can be large relative to explicit fees, making interest on float a potentially significant revenue source. Because this cost is not directly visible in quoted prices or transaction fees and varies with interest rate conditions and settlement timing, transparency about collateral treatment, interest allocation, and related fees is necessary for participants to accurately assess the total cost of trading.

Example:

Imagine an event market where contracts pay $1 if an outcome occurs and $0 otherwise. The platform requires traders to post collateral equal to their maximum possible loss.

Suppose Sarah trades actively. Over the course of a month, she maintains an average open position that requires $10,000 of posted collateral. She doesn’t notice this much because she’s constantly entering and exiting positions, but at any given time roughly $10,000 of her capital is sitting on the platform.

Assume short-term interest rates are 5% annually. That $10,000 of collateral therefore earns about $500 per year, or roughly $42 per month.

If the platform retains the interest and credits Sarah nothing, Alice is implicitly paying about $42 per month in financing cost, even if the platform charges zero explicit trading fees. If her explicit trading fees over the month are only $10, then the hidden financing cost is actually the dominant component of what she’s paying to trade.

Now scale this up to the platform level. If the platform has 5,000 active traders like Sarah, each with $10,000 of average collateral posted, the platform is holding $50 million of float. At a 5% annual rate, that float generates $2.5 million per year in interest revenue. That can easily exceed revenues from trading fees alone, especially in high-turnover markets where collateral is continuously recycled.

If instead the platform credits interest back to users the platform must instead rely more heavily on explicit fees or spreads to cover its costs. That’s why the treatment of collateral matters, and why users need clear disclosure to understand the true cost of participation.

Clearing and counterparty risk

A venue registered as a DCM and backed by a regulated clearinghouse reduces bilateral credit risk because the clearing house stands between counterparties and manages defaults via margin and default rules. That is a central reason why platforms pursue CFTC designations. Federal clearance and central counterparty mechanisms change counterparty risk profiles.

When a trade executed on a DCM is cleared through a Derivatives Clearing Organization, the clearinghouse novates the transaction and becomes the buyer to every seller and the seller to every buyer. As a result, participants no longer face direct credit exposure to one another and instead face exposure only to the clearinghouse. The clearinghouse manages this risk through standardized margin requirements, mark-to-market processes, default funds, and predefined default management procedures designed to ensure continued performance even if a participant fails. If one trader defaults, the clearinghouse absorbs and mutualizes the loss so that non-defaulting counterparties still receive payment. This structure is particularly important for event markets, where payoffs can change discontinuously at resolution and default risk can spike sharply at settlement. Federal regulation and central clearing therefore change the counterparty risk profile from a network of bilateral obligations into a centralized, rule-based system with legally enforceable protections. This reduction in bilateral credit risk is a central reason platforms seek CFTC designation, although the risk is transformed rather than eliminated, since exposure is concentrated in the clearinghouse and depends critically on margin models, governance, and default management rules.

Looking at it from a trader´s perspective

Event markets are tradeable instruments that offer clear, bounded payoffs and the potential to express precise, event-level views. For disciplined traders who treat legal exposure as a risk factor, who read contract rulebooks, and who trade on venues with robust clearing and surveillance, these contracts can be a practical tool. They are not, however, a frictionless or juridically neutral market.

From a pure P/L perspective, event contracts are inexpensive to model at the individual trade level because outcomes and maximum losses are bounded. The cost side, however, is multidimensional, as explicit fees, embedded spreads, collateral interest treatment, and any applied margining system all change true trading economics. Always model gross P/L and then net it down by an explicit cost schedule rather than rely on headline prices alone. Different venues publish different fee schedules and collateral rules.

How people trade event contracts: Market making, hedging and behavioral patterns

Market making and liquidity provision

Where markets are deep enough, market makers quote two-sided prices and collect the spread while managing inventory. Market making in event contracts is conceptually identical to making a market in a thinly traded equity. Dealers must manage inventory risk (exposure to a single event), adverse selection (sudden revelation of information), and the tail risk of an outcome surprise. Inventory management is often harder because the underlying event has discrete resolution and often correlated newsflow. An overnight political leak can move the entire book.

For larger platforms attempting to attract institutional liquidity, market-making incentives (rebates, fee waivers, or designated liquidity provider programs) are normal. The combination of incentives, position limits, and balance sheet capacity impacts the available depth and the realized spreads.

Arbitrage and synthetic constructions

Event contracts can be combined synthetically to express more complex views. Traders construct calendars, straddles and spreads across correlated event outcomes, and when platforms support continuous trading traders arbitrage between related contracts. For instance, a contract on “Party A wins Senate” and contracts on individual state results can be used in combinations to exploit inconsistent probabilities. That arbitrage is effective only when execution costs, position limits, and settlement rules make the composite replicable. Arbitrageurs are the classic source of price discipline. If liquidity and fee structures support it, arbitrage reduces persistent mispricing. But when markets are thin or when contract wording prevents exact replication (e.g. due to different resolution sources), arbitrage is limited.

Hedging real-world exposure

Participants can use event contracts to hedge real exposures. Examples include political risk hedging by corporate treasuries when elections threaten trade policy, or sports-related media companies hedging advertising exposures.

Examples:

      • A multinational company might worry that a new government could impose tariffs affecting its exports. If there’s an event contract that pays out based on that election outcome, the company could aim to offset potential losses. This is a type of hedging against political risk.
      • A media company may depend on ad revenues linked to a sports team’s performance. By using a contract tied to the team’s results, it can hedge against the risk of poor performance reducing revenue.

For hedging to be rational, the contract’s defined outcome must match the corporate exposure precisely, because a mismatch in definition can make the hedge ineffective. Hedging only works correctly if the contract’s payoff is highly correlated with the exposure. If the contract is too broad or doesn’t align perfectly with the company’s risk, it might fail as a hedge or even amplify risk. Examples: If a company fears tariffs on imports from a specific country, but the event contract only pays based on the overall election winner without specifying trade policy, the hedge could be ineffective. Similarly, a contract that pays if a league’s champion is a particular team might not properly hedge ad revenue if the revenue depends on a different performance metric (like attendance or TV ratings).

The bottom line is that event contracts can be rational hedging tools if the contract’s outcome aligns closely with the exposure. Otherwise, the hedge may not work as intended.

Retail behavior and volume dynamics

Retail participants often treat event contracts like entertainment and make speculative “micro-bets”. This behavioral tendency amplifies volatility in sports and political contracts. The entry of retail money increases amplitude and frequency of price moves and can result in short-term dislocations that are exploitable only if transaction costs and margin permit.

Surveillance, manipulation and trade monitoring

Because many events are influenceable or subject to insider information, exchanges that expect professional liquidity invest in surveillance. That function tracks suspicious volume patterns around news, concentration in single accounts, and unusual timing relative to known information events. Exchanges can also provide audit logs and cooperation channels for law enforcement when manipulation is suspected.

The risk of inside trading was highlighted in early 2026, when an anonymous trader made over $400,000 by placing a large bet on a prediction market (Polymarket) just hours before Venezuelan President Nicolás Maduro was captured by U.S. forces. The wager was placed via a newly created account right before the event became public, and it sparked widespread suspicion that the trader had access to insider or nonpublic information. This situation was widely discussed in news media and even prompted lawmakers to propose new regulation to curb insider trading in prediction markets.

The episode is significant because it shows how event markets can be vulnerable: if an actor has access to pertinent non-public information regarding a real world event (e.g. military or government actions), they may profit unfairly, underscoring the need for surveillance and controls much like in traditional exchanges. There is also the risk that being able to make big money from certain events happening could sway decision makers.

The Maduro case is not unique, and there have been other reported controversies in prediction markets involving suspicious trading ahead of planned announcements. For example, analysts and observers have flagged unusual bets on outcomes tied to corporate announcements (such as MicroStrategy’s Bitcoin purchases), where large, anonymous trades moved markets before relevant news was made public.

In December 2025, several anonymous traders placed unusually large bets (approximately $140,000 in total) on a Polymarket prediction market that asked whether MicroStrategy would announce a Bitcoin purchase of >1 000 BTC between December 2–8, 2025. These bets were placed just hours before MicroStrategy publicly disclosed that it had bought 21 550 BTC (circa $2.1 billion). All three wallets involved were new accounts with no prior history, funded immediately before the trades, and concentrated exclusively on that one outcome, a pattern often seen as a classic insider signal. The market’s odds jumped from around 40 % to circa 61.5 % ahead of the announcement, and the traders then collected their winnings. Some event markets have limited surveillance compared with regulated equity or futures exchanges, so patterns like sudden, large, well timed bets can be more likely to go unchallenged. In this case, Polymarket’s leadership stated that such trades were not even prohibited.


It should be noted that the media attention and regulatory focus on the MicroStrategy event isn’t just about prediction markets, it is part of a broader trend where regulators have been looking at unusual market movements before public announcements involving crypto treasury strategies and corporate disclosures. For example, U.S. regulators including the SEC and FINRA have been probing large price movements ahead of crypto related announcements by companies with such strategies, partly spurred by attention around firms like MicroStrategy.

It is also important to remember that while the above are modern examples tied to new forms of trading (prediction markets), traditional markets have long had high profile insider and manipulation cases too, e.g., the Galleon Group insider trading scandal in the U.S., where hedge fund managers and executives were prosecuted for trading on confidential corporate information.

Regulatory mechanics in the United States

The U.S. regulatory debate about event markets largely centers on whether such contracts fall within the Commodity Exchange Act (CEA) and how the CFTC should exercise its statutory authority. Two elements are central to market design and compliance: (a) exchanges and clearinghouses that register under the CEA, and (b) Regulation 40.11 (17 CFR § 40.11), which provides a review mechanism for certain event contracts. The interaction of federal registration and state gaming statutes is currently the main battleground.

Event markets are not a new invention. Humans have been betting on the outcome of certain events for a very long time, and, if we look at the modern event contract, academic and market literature dates back at least a few decades. What is new is the effort by some firms to operate event contracts at scale in the U.S. under federal derivatives rules, rather than as state-regulated wagering products. That shift is what has created the modern regulatory fight, because a platform can now register as a Designated Contract Market (DCM) with the CFTC, list event contracts, and claim federal preemption over state gambling laws. States have disputed that claim in multiple legal venues. The CFTC itself has actively engaged: it defined the relevant rule language in Regulation 40.11 and has recently been moving to clarify where it will draw the line between permissible event contracts and those it will treat as contrary to the public interest. The agency’s posture has shifted over time. Under current leadership, the CFTC has directed staff to withdraw earlier prohibition proposals and to proceed with new rulemaking to define standards. That development is itself a material event for anyone exposed to these markets.

U.S. platforms that operate under federal derivatives rules are currently subjected to strong friction caused by derivatives law interacting with state gambling law, and recent litigation and administrative actions have turned a previously niche topic into a mainstream regulatory controversy. Reporting by main outlets such as Reuters and the Financial Times, along with CFTC notices, track this evolution, and show how market structure choices create legal questions rather than purely commercial ones.

Designated Contract Markets and federal oversight

Exchanges that register as Designated Contract Markets (DCMs) operate under CFTC supervision and are required to comply with reporting, surveillance, and market-integrity rules. DCM designation places platforms under the CEA framework and enables federal oversight, which platforms argue should preempt conflicting state regulation. Notably, the CFTC designated the famous Kalshi platform a DCM in 2020. It later amended the designation to permit intermediated futures trading and third-party clearing under specified conditions.

Federal oversight via the CFTC delivers surveillance, reporting obligations, clearinghouse rules, and a dispute framework that is uniform across states. That reduces some forms of counterparty risk and can improve transparency. It does not automatically immunize contracts from state law claims, nor does it eliminate the risk that courts will hold a particular contract subject to state gambling statutes. The interplay of CFTC registration and state enforcement is a very real and practical issue that is giving rise to litigation in the United States right now.

Regulation 17 CFR § 40.11 and the public interest carveout

Regulation 17 CFR § 40.11 implements Section 5c(c)(5)(C) of the CEA, which provides that the Commission must not list for trading, and a DCM must not list, contracts involving certain excluded commodities unless the CFTC determines that such a contract is not contrary to the public interest.

Note: CFR = Code of Federal Regulations

Regulation 40.11 enables the Commission to request suspension and apply a 90-day statutory review for contracts that reference enumerated or similar activities (for example terrorism, assassination, war, gaming, or other activities the Commission finds contrary to public interest). The 90-day review is the tool that allows the Commission to step in and evaluate whether a listed contract should continue to trade. The rule’s language has been the subject of recent proposed revisions to clarify whether categorical exclusions (e.g., sports, political events) are permitted.

This is what regulation 17 CFR § 40.11 looks like right now, at the time of writing, in early 2026:

17 CFR § 40.11 – Review of event contracts based upon certain excluded commodities

(a) Prohibition. A registered entity shall not list for trading or accept for clearing on or through the registered entity any of the following:
(1) An agreement, contract, transaction, or swap based upon an excluded commodity, as defined in Section 1a(19)(iv) of the Act, that involves, relates to, or references terrorism, assassination, war, gaming, or an activity that is unlawful under any State or Federal law; or
(2) An agreement, contract, transaction, or swap based upon an excluded commodity, as defined in Section 1a(19)(iv) of the Act, which involves, relates to, or references an activity that is similar to an activity enumerated in § 40.11(a)(1) of this part, and that the Commission determines, by rule or regulation, to be contrary to the public interest.

(b) [Reserved]

(c) 90 day review and approval of certain event contracts. The Commission may determine, based upon a review of the terms or conditions of a submission under § 40.2 or § 40.3, that an agreement, contract, transaction, or swap based on an excluded commodity, as defined in Section 1a(19)(iv) of the Act, which may involve, relate to, or reference an activity enumerated in § 40.11(a)(1) or § 40.11(a)(2), be subject to a 90 day review. The 90 day review shall commence from the date the Commission notifies the registered entity of a potential violation of § 40.11(a).

(1) The Commission shall request that a registered entity suspend the listing or trading of any agreement, contract, transaction, or swap based on an excluded commodity, as defined in Section 1a(19)(iv) of the Act, which may involve, relate to, or reference an activity enumerated in § 40.11(a)(1) or § 40.11(a)(2), during the Commission’s 90 day review period. The Commission shall post on the Web site a notification of the intent to carry out a 90 day review.

(2) Final determination. The Commission shall issue an order approving or disapproving an agreement, contract, transaction, or swap that is subject to a 90 day review under § 40.11(c) not later than 90 days subsequent to the date that the Commission commences review, or if applicable, at the conclusion of such extended period agreed to or requested by the registered entity.

Self-certification and the “list it unless CFTC stops it” dynamic

Under current exchange practice, many DCMs can self-certify that new contract listings comply with the CEA and CFTC rules. In practice, that allows an exchange to list a contract and let trading begin unless the Commission initiates review. That dynamic supports product innovation but also creates political and legal pressure when controversial contracts are listed. The self-certification model is why a platform can list contracts (including sports and political contracts) and make them available without delay and without specific pre-approval from the CFTC.

What we now have is a situation where states or advocacy groups pay attention to event market platforms and challenge controversial contracts right away, hoping to trigger a CFTC review or litigation. If the CFTC decides to review a listed contract, it can order the exchange to pause trading while the review is ongoing. The pause will continue until the Commission makes a determination.

Recent CFTC posture and rulemaking activity

The CFTC’s position toward event contracts has evolved. The agency proposed amendments in 2024 intended to clarify Rule 40.11’s scope, creating substantial debate. As litigation and state actions proliferated, the CFTC issued a staff advisory in 2025 warning registrants about sports-related contracts. That advisory then became a point of contention. In late January 2026, new CFTC leadership directed staff to withdraw the 2024 proposal and the 2025 advisory, and to prepare a fresh rulemaking aimed at setting clearer standards for event contracts. That policy reversal signals the agency’s recognition that the present framework produces legal uncertainty and that a clearer, durable rule would reduce patchwork litigation. Traders should interpret this as an ongoing regulatory rewrite, not a settled field.

Litigation and the state vs federal conflict: Cases, cease-and-desist actions and recent developments

Regulatory mechanics matter because enforcement follows. Over the last two years, the contested line between federally regulated derivatives and state-regulated wagering has been litigated in several venues. These disputes are the proximate cause of the headlines about cease-and-desist letters, preliminary injunctions, and split judicial rulings.

When a state issues a cease-and-desist, platforms commonly react in one of two ways: they either remove the offending contracts for accounts geographically located in the state or they sue the state asserting federal preemption and seek injunctive relief. Both responses are operationally complex. Geofencing markets reduces available liquidity and creates execution fragmentation, while litigation is expensive and uncertain. From a trading perspective, legal headline risk can cause large, abrupt price moves in affected contracts because the availability of markets in some states can materially change participation and depth.

The litigation path is long. Preliminary rulings, temporary restraining orders, and early injunctions are interim outcomes that can be reversed on appeal. The split between federal courts on the issue increases pressure on the CFTC to articulate a clear national rule so that exchanges and investors know which products are likely to survive. In at least one reported instance, the CFTC withdrew an appeal related to election contracts. The litigation docket will be active for some time and will materially affect the practical availability of certain contract categories.

The reported instance where the CFTC withdrew an appeal related to election contracts was in the litigation involving KalshiEx LLC’s political event contracts. KalshiEx, a regulated U.S. derivatives exchange, created “event contracts” tied to the outcomes of U.S. elections, such as which party would control Congress. The CFTC originally disapproved of these political event contracts, arguing they were contrary to the public interest and exceeded its authority under the Commodity Exchange Act. Kalshi challenged the CFTC’s decision in court and won in federal district court, which ruled that the CFTC had exceeded its statutory authority by banning those contracts. The CFTC then appealed that ruling to the U.S. Court of Appeals for the D.C. Circuit. In 2025, the CFTC voluntarily withdrew its appeal of that decision, effectively leaving the lower court ruling in place and allowing Kalshi to continue offering election outcome contracts. This was widely reported in media coverage of the prediction market regulatory landscape.

Kalshi’s 2020 DCM designation was an early test of whether event contracts could be regulated under the Commodity Exchange Act (CEA). Since listing event contracts more widely, particularly sports and political contracts, Kalshi has attracted state enforcement actions and litigation. The sequence of events shows how rapidly legal outcomes can vary by forum and state.

Representative state actions: Tennessee and Nevada

Multiple states have acted against event market venues offering sports or other event contracts without state gaming licenses. When it comes to sports betting, some states have an outright ban, while other states have legal and regulated sportsbetting for venues that hold a state-license.

Tennessee

Sports betting is legal in Tennessee, but only through online venues approved by the Tennessee Education Lottery, which regulates sports betting in the state. Tennessee’s sports betting regulator has issued cease-and-desist letters to several event market venues that are operating without a Tennessee license, including Kalshi and Polymarket, alleging unlicensed sports wagering and raising concerns about under-21 participation and consumer protection.

A federal judge temporarily restrained Tennessee from enforcing the ban against Kalshi in January 2026, concluding that Kalshi was likely to succeed on federal preemption and other claims at the preliminary stage. A hearing for a preliminary injunction followed.

Nevada

Nevada’s federal court has taken a different path than the federal court in Tennessee. In November 2025, a federal judge in Nevada ruled that Kalshi is subject to Nevada gaming rules, undermining Kalshi’s claim that federal derivatives jurisdiction displaces state gaming law. The Kalshi case in Nevada was heard in the U.S. District Court for the District of Nevada, and federal judge who issued the ruling was Chief Judge Andrew Gordon. The decision required careful statutory analysis and turned on how Nevada’s gambling statutes and the specific form of Kalshi’s sports contracts aligned with state law. The Nevada decision was widely reported and is one of several rulings that create a fractured judicial map.

To understand the background, and why this case got so much attention, we need to know that Nevada is one of the oldest and most well-established legal sports betting markets in the U.S. and it commonly serves as the benchmark for how legal sports wagering operates in the country. Nevada has allowed sports betting since 1949, long before the federal ban (PASPA) was overturned in 2018. It was the only state that had legal, full-scale sports betting during the federal ban, which is why it became a global hub for betting on professional and college sports. With that said, Nevada is not a laissez-faire state when it comes to sportsbetting, and sportsbooks must be licensed and heavily audited. The main authorities are the Nevada Gaming Control Board (NGCB) and the Nevada Gaming Commission (NGC). Nevada enforces strict rules on responsible gambling, including age limits (21+) and monitoring for problem gambling, and Nevada sportsbooks pay 6.75% tax on gross gaming revenue (GGR). Even though this is lower than most other states with licensed sportsbetting, the high volume means that sportsbetting still generate significant tax revenue for the state. In 2024, Nevada sportsbooks generated approximately $482 million in GGR, which at 6.75% produced roughly $32.5 million in state tax revenue from sports betting.

Policy and market-integrity objections: Consumer harm, manipulation, insider incentives and political risk

Arguments against particular event contracts fall into policy categories where trading intersects social harm and governance concerns. These objections are commonly advanced by state regulators, some members of Congress, and advocacy groups, and they can impact the public interest analysis that appears explicitly in Regulation 40.11.

Consumer harm and problem gambling concerns

Critics argue that event markets, especially when they cover sports and politics, function as a kind of gambling wrapped in financial jargon. Platforms that facilitate continuous trading, low minimum stakes, and accessible mobile experiences can encourage high-frequency speculative behavior. Even though each contract’s maximum loss is bounded, repeated trading can produce significant cumulative losses. Regulators point to how problem gambling protection standards included in state wagering regimes (e.g. age restrictions, advertising controls, customer suitability checks, and responsible-gaming programs) are not uniformly required in federal derivatives frameworks. These differences are a frequent basis for state enforcement actions. Coverage of cease-and-desist efforts highlights concerns that platforms allow users under age thresholds required by state gambling law to participate.

Market integrity: manipulation and insider trading

Event markets raise novel market-integrity concerns because the underlying events are often influenceable and resolvable by a small set of actors. Examples include political outcomes, corporate actions, and sports outcomes where participants or officials can affect the result. Thin markets and anonymous or pseudonymous trading compound the risk. A person with material non-public information can trade on that information and profit, and detecting abusive trading is harder when turnover is fragmented across platforms. High-profile suspicious trades (such as late bets on dramatic political events) have attracted press attention and regulatory scrutiny. These episodes prompt calls for enhanced surveillance and information-sharing protocols.

Political and governance objections

Political event markets attract additional objections, and the arguments here are not purely economic. Allowing open financial markets on election or coup outcomes may create perverse incentives. Opponents worry that monetizing political events could encourage interference, distort public perception by lending markets a veneer of authority, or encourage actors to act in ways that alter outcomes for profit. The “public interest” language in Regulation 40.11 reflects this concern. Even when labeled a derivative, certain contracts may can still create incentives that a regulator may judge inconsistent with public welfare.

Moral-hazard objections and influenceability

Several event categories are susceptible to influence. Awards voting, internal corporate decisions, or small-scale governmental actions can be influenced by the same actors who have the capacity to trade or cause trades to be placed. This creates a dual risk; both actual manipulation and the reputational or political risk that public perception of manipulability creates even if manipulation is rare.

Practical implications for traders and investors: How to price legal, regulatory and operational risk

If you trade in event markets, the product is a financial instrument plus legal exposure. The legal exposure is not an externality; it is a tradeable risk factor that can dominate market movements. Traders should fold legal/regulatory risk explicitly into valuation and position sizing.

Model the regulatory risk

For any event contract that is controversial (sports, political, or otherwise contestable), assume a regulatory probability that the contract will be delisted, limited in certain jurisdictions, or face forced refunds. That probability should be backed out of market liquidity and recent enforcement actions. Use scenario analysis: if a given contract is geofenced in several large states, what is the impact on bid-ask and terminal liquidity? If an injunction prevents trading for 30 days, how will open positions be handled? Model the cost of forced liquidation, refund, or litigation explicitly.

Treat headline risk as a primary factor

Legal and regulatory headlines can wipe out markets quickly. A cease-and-desist or a court order dissolving trading in a mid-volume contract can turn a $0.20 position into zero by closing the door to buyers. If you operate intraday, build event monitoring into your desk’s watchlist. If you hold positions overnight or across political windows, size down for the increased legal tail.

Check the contract rulebook before trading size

Read the contract specification. Who is the resolution source? Is there an appeals window? What happens if the source revises data? Is the contract explicitly geofenced in certain US states? What are the platform’s rules on collateral and margin? Often the settlement rules contain the operational answer to the scenarios that most worry traders.

Prefer venues with robust surveillance and clear dispute mechanics

Use DCMs or venues that publish clearinghouse rules and surveillance protocols. Central clearing reduces counterparty default risk and typically implies higher operational maturity. Being a DCM does not immunize the venue from state legal action, but it reduces counterparty credit risk and adds regulatory reporting and monitoring that helps identify abusive trades.

Liquidity and legal fragility

When comparing prices across platforms, require a liquidity and legal premium. A thin market that trades at $0.50 on a lightweight platform is not the same as $0.50 on a well-cleared DCM with global liquidity. Apply an explicit “platform risk discount” if the contract is likely to face state regulatory pressure.

Hedging and portfolio construction

If you use event contracts for hedging, will the hedge be legally enforceable? Will counterparties honor settlement even if a platform is embroiled in litigation? Consider trading the same view across multiple, legally distinct venues when possible, to reduce single-platform legal risk.

Examples of three well-known prediction market venues

Kalshi

Kalshi is a U.S.-based prediction market platform where traders can buy and sell contracts on the outcomes of real world events, from politics and economic data to weather and sports outcomes. To better distribute prediction data, the platform has struck media partnerships with major news outlets, including CNN and CNBC.

Kalshi users can trade on outcomes like election results, inflation figures, or even whether a company will IPO by year end. Kalshi offers yes/no contracts that settle at $1 if the event happens and $0 if it doesn’t. Prices between $0 and $1 reflect the market’s implied probability of the event occurring.

Kalshi is registered with the U.S. Commodity Futures Trading Commission (CFTC) as a Designated Contract Market (DCM) and is fully regulated under the Commodity Exchange Act. This federal status enables it to offer event contracts legally in the U.S., though it faces ongoing state level legal challenges, including lawsuits claiming its sports betting contracts are illegal.

PredictIt

PredictIt is a political prediction market that lets users trade contracts on political outcomes, especially U.S. elections and government related questions.

PredictIt uses binary “Yes” and “No” contracts for each event, and each contract is priced between $0.01 and $0.99, where the current price reflects the market’s implied probability of an outcome.

If the event happens, “Yes” contracts settle at $1.00 and “No” contracts go to $0.00. If the event doesn’t happen, “No” contracts settle at $1.00 and “Yes” go to $0.00. This means a correct prediction yields $1 per share and an incorrect one yields nothing.

Historically, PredictIt operated under a special CFTC “academic use” exemption, allowing small scale markets mainly for research and forecasting. That exemption was restructured in 2025, and PredictIt won approval to expand operations and launch as a fully regulated market with higher position limits and more flexible political trading. PredictIt now operates with CFTC approved regulatory status, putting it on a more stable legal foundation than before.

Polymarket

Polymarket began as a crypto native, blockchain based prediction market where users speculate on outcomes ranging from politics and sports to economic or social events. After facing U.S. enforcement actions and a 2022 ban for operating without registration, Polymarket acquired a CFTC licensed exchange and received regulatory clearance to re-enter the U.S. market legally. It also received a CFTC no action letter, which relaxes some reporting and recordkeeping requirements under certain conditions.

In order to be able to operate legally in the U.S., Polymarket acquired the CFTC licensed exchange and clearinghouse QCEX and secured regulatory approval. Polymarket completed the acquisition of QCEX in July 2025, and the CFTC then granted Polymarket clearance, including an amended designation and a no action letter. Under this new U.S. regulatory structure, U.S. users cannot trade directly with crypto wallets as before. Instead, trading happens through regulated intermediaries such as futures commission merchants or brokers. Access rules, compliance, and settlement follow CFTC regulated derivatives standards, rather than exclusively on chain smart contracts.

Polymarket now operates as two distinct entities: a global crypto-native platform and a U.S.-regulated market. The dual structure allows Polymarket to maintain its global crypto audience while simultaneously offering a U.S. compliant venue for U.S. participants, balancing innovation with regulatory adherence. The U.S. entity operates through intermediaries, requiring fiat accounts or approved brokers rather than direct crypto wallet interactions. The range of events is narrower.

The global branch is the continuation of Polymarket’s original model, built on blockchain technology and allowing users worldwide to trade prediction contracts using cryptocurrency, primarily USDC, on the Polygon network. This version offers a wide array of markets, including politics, sports, finance, entertainment, and other global events. Settlement occurs automatically through smart contracts, and participation is largely unrestricted outside the United States, enabling exotic or niche markets that would be impermissible under U.S. law.

DeFi binary options

Contributor Image
Written By
Contributor Image
Written By
William Berg
William Berg is a legal expert with a focus on securities law and a long track record in the trading industry.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Updated

In recent years, the world of binary options have been shook up by the introduction of DeFi binary options. DeFi, short for decentralized finance, denotes financial solutions that rely on blockchain technology instead of banks and other traditional intermediaries. DeFi is for instance used to send money, borrow, lend, trade assets, and earn interest, using smart contracts instead of banks. No single company or bank controls the system, transactions run on public blockchains, and the so-called smart contracts are actually just pieces of code that automatically executes agreements. Typically, you do not need an ID or credit check to use DeFi.

So, what does this have to do with binary options trading? Well, DeFi binary options do not rely on a centralized broker or exchange. Instead, you trade on the blockchain using smart contracts. Instead of a binary options platforms internal pricing engine, the setup is backed by liquidity pools and decentralized oracles (systems that bring real-world data into a blockchain in a trust-minimized way).

Before you decide if you want to jump into the world of DeFi binary options, it is important to understand how it works, and be aware of the risks and quirks it involves, including everything from smart contract exploits to oracle delays. If you decide to engage with these products, do so with modest capital, rigorous checks, and the expectation that the environment is experimental. Treat any DeFi binary exposure as speculative and design strict risk controls around it.

DeFi binary options are an innovative intersection of prediction markets and automatic derivatives settlement. While they offer transparent code driven settlement and new ways to express short dated views on crypto and on chain events, they also inherit the full range of DeFi hazards, including smart contract bugs, oracle manipulation, thin liquidity, Maximal Extractable Value (MEV), and unclear regulation. Compared to conventional binary options platforms in lax offshore jurisdictions, DeFi binaries remove some counterparty and withdrawal risks, but replaces them with technical and oracle risks.

DeFi binary options

The basics

DeFi binary options are fixed-outcome contracts implemented on blockchains. Like traditional binary options, they pay a predetermined amount if a specified condition is true at expiry, and pay nothing if it is false (i.e. you lose your entire stake).

The crucial difference between traditional binary options and DeFi binaru options is that for the latter, the contract logic, collateral management, and settlement are handled by smart contracts on a public ledger and not by a central broker. In practice that means the rules are code, trading history is on-chain,

and settlement usually depends on an oracle feeding off-chain price data to the smart contract.

Under the hood, a DeFi binary option is usually a tokenised claim. You buy a token that represents the “yes” side of an event and another party holds the “no” side, or you buy from an automated market maker that prices those claims arithmetically. At expiry, the smart contract consults the oracle and distributes collateral according to the outcome.

Instead of a direct counterparty, users often trade against an automated market maker, such as an LMSR or similar bonding-curve models, that prices those claims mathematically. LMSR stands for Logarithmic Market Scoring Rule, and is a type of automated market maker (AMM) used in prediction markets and DeFi binary options to price and manage trades of outcome tokens.

Sometimes there is a direct human counterparty, but more frequently, your counterparty is a liquidity pool and not a specific trader. Liquidity providers typically earn money from trading fees and from the spread/ pricing edge.

Mechanics and typical flows

A trade begins with selecting an event and staking collateral. The event can for instance be simple price direction for a specific timestamp, a prediction market question, or a composite event that depends on several inputs. Collateral normally sits in the smart contract and is either provided by a central liquidity pool or by counterparty holdings. Pricing is derived either from user driven order books, from an AMM curve that maps probability to price, or from peer matched offers. Once you place a position you cannot usually change it, and the contract will enforce expiry and settlement automatically. The reliability of the final payout depends on the oracle architecture, the smart contract code, and the liquidity rules baked into the protocol.

Risk management

Some DeFi providers implement different ways to reduce some classic binary problems when it comes to risk management. Some allow early exit by selling your position back into the pool, others let you hedge with the opposing token, and a handful add mechanisms to limit manipulation around expiry.

Prediction markets and derivatives protocols

DeFi binary options appear in two main forms on Ethereum and other smart contract platforms. One is prediction markets, which operate like decentralised betting exchanges using pooled liquidity and on chain resolution. The other is derivatives protocols that offer short dated digital contracts on prices via Automated Market Makers (AMMs) or isolated pools. You can also find hybrid offerings that wrap centralized data feeds into smart contract settlement to offer binary style payoffs for non-crypto assets.

Access usually requires a crypto wallet, gas to transact, and a source of collateral token, most commonly stablecoins. Liquidity and market choice are still narrower than in mainstream derivatives venues, so tradable events and expiry windows may be limited compared to centralized brokers. If you’re looking for exposure to a non-crypto underlying asset, verify whether the protocol’s oracle has robust access to the required price source.

What assets and events are available?

As of 2026, the most common type of underlying asset are cryptocurrency exchange rates, on-chain metrics, and protocol specific events. Examples include whether the BTC/USD exchange rate will exceed a certain price at a given time, whether ETH supply will hit a certain threshold, or the outcome of governance votes.

Some prediction markets accept broader event types, including sports, governmental elections, and macro data releases, but those require specialized oracles and often carry higher manipulation risk.

What are on-chain metrics?

On-chain metrics (blockchain state variables) use blockchain data directly. They are quantitative metrics derived from on-chain activity and will be trustlessly observable at settlement. Examples of common on-chain metrics are Total Value Locked (TVL), gas usage, number of active addresses, and transaction count.

Examples:

Will Arbitrum TVL be above $3B at epoch end?
Will Ethereum daily gas used exceed 120B by Friday?

What are protocol-specific events (state transitions)?

Protocol-specific events are binary yes/no outcomes tied to smart contract or governance events, such as governance votes, contract upgrades, and emergency shutdowns. They are discrete events that either happen or don’t, and they are often deterministic from contract state.

In addition to speculation, protocol-specific binary options are used to hedge protocol risks.

Examples:

  • Will Proposal #198 pass governance by block X?
  • Will Protocol Y deploy v3 before August 1?
  • Will this protocol’s insurance fund be triggered?

Can´t I speculate on stock prices, forex, etc?

Yes, you can, but the assortment of DeFi binary options based on equity, forex, commodity prices, etcetera is still pretty limited. Protocols need to connect to high quality, multi source oracles to offer speculation on these type of assets. Practical availability is limited, because those oracles must be reliably permissionless or trusted enough to satisfy the contract’s settlement rules. We can therefore expect the majority of liquid markets to remain crypto-native. There is room for a trailblazing platform to build credible, decentralised price feeds for traditional assets.

Common fees and hidden cost

Expect protocol fees (a percentage of stake or payout), AMM slippage, spread costs, and network gas costs. Oracle fees are sometimes paid by users. If you use wrapped tokens or bridges, conversion and bridge fees add to the cost. For short-expiry trades, gas can be a significant percentage of your stake on high-fee chains, and you need to account for this when planning small trades.

Technical, economic, and legal risks

DeFi binary options combine the risks of binary products with the particular hazards of blockchain finance. Examples of important risk categories to consider:

  • Smart contract risk. Bugs in contract code can allow theft, incorrect settlement, or state corruption. Audits reduce but do not remove this risk. Complex settlement logic increases the probability of edge case failures.
  • Oracle risk. If the contract depends on a single price feed, manipulation or outages can produce incorrect settlement. Multi source oracles and time weighted averages mitigate this but introduce latency and partial settlement complexity.
  • Liquidity risk. Many DeFi binary pools are shallow. Large positions can move the price dramatically and early exits may be expensive or impossible at times of stress.
  • Design and economic edge. Many binary-like markets have a built in house edge through spreads, payout curves or impermanent loss for liquidity providers. Even where the market is permissionless, expectation math usually favors the protocol or the LP unless you have a demonstrable statistical edge.
  • Front running and MEV. Because trades are public before execution, miners and validators can reorder or sandwich transactions to extract value. That can distort fills and settlement for time sensitive binaries.
  • Regulatory and legal risk. Involving both retail-accessable binary options and blockchain solutions, DeFi binary options operates in a gray and complex regulatory spaces. Selling binary options to retail clients (non-professional traders) is banned or heavily restricted in many jurisdictions, and this raises the risk that services will be blocked, delisted by custodial on-ramps, or targeted by enforcement actions in such countries. Using DeFi does not eliminate this type of legal risk.
  • Operational and counterparty risk. While decentralised protocols can reduce counterparty default risk, liquidity providers and front ends remain points of failure. UI bugs, withdrawal freezes on connected bridges, or third party oracle outages can also prevent you from accessing funds or settling positions cleanly.

How DeFi binary options compare with traditional retail binary options

For many, the appeal of DeFi binary options is largely transparency: trades and collateral on chain, immutable code, and public history. With on chain contracts you can inspect formulas, see real time liquidity, and trace settlement flows. Conventional retail binary options platforms have been criticized for their lack of transparency, especially considering the conflict of interest that comes from having the platform being both your broker and your counterparty in each trade. Conventional retail binary options platforms are typically based in offshore locations with lax trader protection rules, where they are not forced to be transparent, and where they are not strictly supervised by any financial authority that ensures the fair treatment of traders. Unsurprisingly, many users of offshore brokers are reporting problems with withheld withdrawals, opaque terms and conditions, and manipulated price feeds.

Since the conventional retail binary options industry is known to include quite a lot of fraudsters and sketchy platforms based in lax offshore locations, the transparency of the DeFi binary option can feel like a breath of fresh air. It is important, however, to remember that transparency is not automatically the same as safety. A DeFi contract can contain exploitable bugs, and public transaction data makes sophisticated attacks easier.

Regulatory recourse vary significantly depending on which route you decide to go. With a properly regulated broker supervised by a powerful financial authority in a country with strong trader protection rules, dispute resolution will be accessible, and issues can be escalated in a meaningful way. With offshore brokers in lax jurisdictions, recourse is much more limited. With DeFi binary options, the legal situation will be gray and complex, and proving wrongdoing and obtaining remediation in DeFi is still both technically and legally difficult.

Offshore brokers in lax jurisdiction are associated with practices that disadvantage clients, like price feed manipulation, unreasonable account freezes, and opaque bonus rules. DeFi protocols can eliminate some of those practices through code, but they introduce new failure modes. In short, DeFi removes certain counterparty risks while adding technical and oracle risks. Neither environment is risk free; they are just different risk portfolios.

Practical due diligence and safer practices

If you consider trading DeFi binary options, treat the activity as speculative and apply a strict due diligence routine. Check whether the smart contracts have public audits and whether the audit firms are reputable. Inspect the oracle design: multi source, decentralised aggregation, and time weighting are preferable. Evaluate liquidity depth and historical volume. Test small deposits and small trades, and confirm withdrawal paths work through any bridges or wrapped token flows you need to use. Use wallets with hardware key protection and enable transaction review tools to detect suspicious behavior. Consider whether insurance pools exist for the protocol and read the fine print. Many “coverage” schemes have narrow triggers and limited capital.

Just as with other types of speculative trading, risk sizing rules are essential. Binary payoffs are all or nothing, and small stakes and conservative bankroll rules need to be in place to reduce the chance of rapid ruin. Limit the capital you allocate, set session loss caps, and weekly caps. Do not adhere to any strategy that involves doubling down after a loss.

Make sure you understand the legal framework for both DeFi and binary options in your jurisdiction before you proceed.

Examples of use cases

While many traders begin with short-term speculation, the programmability of on-chain contracts enables a wider range of strategies that extend beyond simple “higher or lower” bets.

  • Short-term speculation and event-driven trading remain the most straightforward applications. DeFi binary options allow traders to express views on near-term price movements or specific outcomes tied to real-world events, such as macroeconomic announcements or elections. Platforms like Polymarket further blur the boundary between trading and prediction markets by offering binary-style contracts on topics that span crypto assets, financial events, and even sports outcomes.
  • Another common approach is hedging volatility with on-chain options. Crypto markets can move sharply, especially around major announcements, and some traders use DeFi binary options as a fast, tactical hedge. For instance, a trader holding Bitcoin who anticipates heightened volatility may open a short-term downside position to partially offset potential losses during turbulent periods.
  • A less common type of use case involves yield generation and liquidity incentives. DeFi options platforms are typically supported by liquidity pools, and participants who stake assets into these pools may earn a portion of trading fees or protocol-issued token rewards. Returns can vary significantly, ranging from relatively modest yields to more attractive levels depending on market conditions. Note: If traders collectively profit against the pool, liquidity providers absorb the losses.

DeFi Binary Options History and Development

The development of DeFi binary options illustrates a steady evolution from theoretical constructs to functional on-chain products. Beginning with Ethereum-based prediction markets in the mid-2010s, the field has grown through experimentation with liquidity pools, oracle integration, and protocol-specific innovations. Dedicated platforms emerged in 2020–2021, bringing short-term crypto derivatives fully onto decentralized networks. Along the way, the acknowledgment of risks associated with MEV, thin liquidity, and oracle vulnerabilities have driven improvements in contract design.

Early Roots: Prediction Markets

The conceptual foundations of DeFi binary options can be traced backed to the early decentralized prediction markets. One early trailblazer was Augur, which launched on Ethereum in 2018 after several years of development, enabling users to create and trade markets with binary outcomes. For instance, users could wager on whether a specific cryptocurrency would reach a particular price by a certain date or whether a political event would occur. Although Augur and similar platforms such as Gnosis were framed as prediction markets rather than explicit financial derivatives, economically they mirrored binary options. Traders assumed positions that paid out fully if an event occurred and traders would lose their entire stake if the event did not occur. These early systems demonstrated that smart contracts and decentralized oracles could resolve binary outcomes automatically.

Despite their innovation, early on-chain prediction markets had notable limitations. Transaction costs on Ethereum were high, especially during network congestion, and market liquidity was often thin. The user experience was complex, as traders needed to understand market creation, tokens staking, and oracle resolution mechanisms. These constraints limited mainstream adoption. Still, the early prediction markets established critical proof of concept, paving the way for more sophisticated financial products. Evidently, smart contracts could enforce the settlement of binary outcomes reliably.

2019-2020: Increased sophistication

The next major evolution occurred around 2019–2020, as the broader DeFi ecosystem began to mature. The rise of automated market makers (AMMs), liquidity pools, and composable smart contracts enabled a shift from peer-to-peer prediction markets to pool-based binary options and short-dated derivatives. Instead of relying on individual counterparty matching, traders could now interact with a pool of liquidity that automatically quoted prices and paid out on settlement. This innovation aligned closely with traditional binary options mechanics.

During this period, developers experimented with various ways to make on-chain binary options more accessible, reliable, and responsive to fast-moving markets. Protocols began integrating oracles for real-time pricing, enabling contracts to settle based on accurate market data. Smart contract design evolved to include expiration windows, automated payouts, and risk management parameters, reflecting lessons learned from both early prediction markets and traditional finance. These innovations reduced friction for traders and increased confidence that contracts would settle fairly and efficiently.

2020-2021: Dedicated DeFi Binary Options Protocols

By 2020–2021, dedicated DeFi binary options platforms began to appear, representing a clear evolution from the experimental phase. Projects such as Thales, Hegic, and PRDT Finance offered explicit “up/down” or “in/out” contracts on crypto assets, combining the predictability of binary outcomes with DeFi’s advantages, especially decentralization, composability, and transparency. These platforms were designed to handle short-term speculation, hedging, and event-driven trading, and they often featured automated settlement and oracle-based pricing to reduce operational risk.

Thales, for example, allowed users to take positions on the direction of cryptocurrency prices at a specified expiry. Hegic experimented with options pools and algorithmic pricing mechanisms, while PRDT Finance expanded binary options across multiple chains, including Binance Smart Chain and Polygon.

At the same time, Augur and other prediction-market protocols continued to evolve, increasingly incorporating financial use cases beyond political or social outcomes. This period marked the formal convergence of DeFi and binary options, creating products that were functionally similar to their traditional counterparts but fully decentralized.

2022 and Beyond: Enhancements and Risk Mitigation

As DeFi binary options matured, developers and researchers increasingly addressed the structural risks inherent in short-term, on-chain derivatives. Two key areas of innovation were oracle design and blockchain-specific risks. Price oracles became more robust, moving from single-point feeds to aggregated sources and time-weighted averages to prevent manipulation by capitalized traders. Similarly, the community became more aware of Maximal Extractable Value (MEV) risks, where validators or bots could profit by reordering, front-running, or sandwiching transactions in a block. These insights influenced contract design, leading to delayed settlement windows, slippage limits, and other mechanisms aimed at mitigating exploit opportunities.

Liquidity considerations also shaped development. Early DeFi binary options often suffered from thin liquidity, which created large spreads and increased vulnerability to manipulation. Over time, protocols incorporated liquidity incentives and yield farming mechanics, encouraging users to stake assets in option pools. This not only improved execution quality but also created an intersection between trading and passive income strategies. However, protocol designers had to balance incentives carefully, as concentrated liquidity in short-term contracts can still be exploited if market participants collude or if MEV behaviors dominate settlement timing.

Current Landscape

Today, DeFi binary options remain a niche but evolving segment of the decentralized finance ecosystem. Platforms like Thales, Injective, PRDT Finance, and Hegic offer a variety of contracts with different expiries, underlying assets, and settlement mechanisms. Meanwhile, prediction market platforms such as Augur continue to blur the lines between event speculation and financial derivatives. The history of DeFi binary options reflects a broader trend in decentralized finance: the gradual translation of traditional financial instruments into programmable, trustless smart contracts.

While adoption remains limited compared to perpetual futures, spot trading, or lending protocols, DeFi binary options have demonstrated the potential for innovative risk management and speculative strategies in a fully decentralized context. They also highlight the ongoing need for careful design around oracle reliability, liquidity depth, MEV protection, and user education. As developers continue to refine protocols and integrate lessons from early markets, the next generation of DeFi binary options may become faster, more secure, and more accessible, even if regulation and user caution continue to shape adoption.

FAQ for DeFi Binary Options

What are DeFi binary options?

DeFi binary options are fixed-outcome contracts written in smart contracts on a blockchain. The contract defines a yes/no question tied to an observable event (for example “will ETH/USD be above $3,000 at 12:00 UTC?”). Traders stake collateral into the contract or buy outcome tokens. At expiry, the contract consults an oracle and automatically distributes the collateral to winning holders while losers get nothing. Functionally, they mirror traditional binary options in payoff structure, but settlement, collateral handling, and record keeping are on-chain.

How is a DeFi binary option executed and settled?

Execution typically happens in one of three ways: peer-to-peer matching, an on-chain order book, or an automated market maker (AMM) that prices the yes/no tokens. Once you place a position it is encoded in the contract state. At expiry the smart contract reads a price or an event result from an oracle and executes the settlement rules in code — moving funds from the pool to winning addresses. Settlement is automatic and auditable on the ledger, but it relies entirely on the oracle and the correctness of the smart contract.

What role do oracles play, and why do they matter?

Oracles provide the off-chain price or event data the smart contract needs to decide outcomes. The oracle design (single source vs multi-source, time-weighted average vs instantaneous price, decentralised vs trusted provider) determines the settlement reliability and the vulnerability to manipulation. A weak or single-point oracle can be spoofed or suffer outages, producing incorrect settlements. Stronger designs use multiple feeds and aggregation logic to make manipulation and downtime more difficult.

What assets or events can you trade with DeFi binary options?

Most liquid DeFi binary markets centre on crypto native underlyings and on-chain metrics. Common examples include price levels for BTC, ETH, major tokens, liquidity pool metrics, or protocol governance outcomes. Some platforms extend to traditional assets (stocks, FX, commodities) via reliable off-chain oracles, but those markets are less common. Expect the most consistent liquidity and variety in crypto native markets.

Where can I trade DeFi binary options?

You trade them on blockchain-based platforms and prediction market contracts deployed on smart contract chains. (Ethereum and compatible L2s are common.) Access requires a compatible wallet, native token or stablecoin for collateral, and often gas to submit transactions. Liquidity and market variety differ by protocol. Some decentralised derivatives protocols host binary products as part of a broader derivatives suite, while dedicated prediction market projects focus on event options.

Can you close or exit a position before expiry?

That depends on protocol design. Some systems allow early exit by selling your outcome token back into an AMM or to another counterparty, which lets you lock a partial profit or cut a loss. Others are strictly fixed-expiry, which means that once you buy, you must await settlement.

Early exit capability improves risk control but requires liquidity in the secondary market, something many small pools lack.

What are the main technical risks?

Smart contract bugs, incomplete audits, and complex settlement logic are primary technical risks. Even audited contracts can contain exploitable edge cases. Bridge and wrapper contracts used to move collateral between chains introduce additional attack surface. Users face the risk of fund loss due to logic errors, reentrancy, incorrect event handling, or admin keys that can be misused. Code visibility helps (you can read contracts on-chain) but understanding subtle vulnerabilities can be difficult for inexperienced users.

What about oracle and market-manipulation risks?

Oracles that depend on point-in-time price snapshots or thin liquidity sources are vulnerable to influence by well-capitalized traders. At the same time, MEV behaviors (such as validator reordering, front-running, and sandwich attacks) can skew price observations and affect execution around sensitive settlement windows. While designs that incorporate time-weighted pricing, multiple data sources, and enforced delays help mitigate these issues, they cannot fully remove them. In practice, manipulation risk increases as liquidity becomes more concentrated and contract expiries become shorter.

Note: MEV (Maximal Extractable Value) is the additional profit that can be captured by controlling or exploiting transaction ordering, inclusion, or timing within a block on a blockchain.

It arises because transactions are public before confirmation (via the mempool), executed in a specific order, and financially sensitive (DEX trades, liquidations, oracle updates, expiries).

What is a mempool?

A mempool (short for memory pool) is the place where a blockchain node keeps valid transactions that have been submitted but not yet confirmed in a block. Nodes broadcast transactions to the mempool, where they wait to be picked up by miners or validators, usually prioritized by gas fees or network rules. For DeFi binary options and other smart contract-based derivatives, this queuing process is crucial because transaction ordering can directly impact payoffs.

MEV (Miner/Maximal Extractable Value) refers to profits that miners or validators can extract by strategically reordering, including, or censoring transactions in a block. Common MEV behaviors include front-running (inserting one’s transaction ahead of a profitable one), sandwich attacks (placing transactions immediately before and after a target to exploit price changes), and general transaction reordering. For short-term options or event-driven contracts, MEV can significantly affect outcomes. A front-run on an options trade could alter the underlying price just before settlement, while sandwich attacks could inflate slippage, reducing expected payoffs. Consequently, traders face additional execution risk beyond market volatility, highlighting the importance of mempool transparency, gas optimization, and MEV-aware strategies when trading time-sensitive DeFi derivatives.

How does liquidity affect trading and pricing?

Just as with traditional financial trading, liquidity determines how easily you can enter, exit or hedge positions without moving the market. Shallow pools produce wide bid/ask spreads and significant price impact for modest-sized trades. AMM-priced binaries embed a curve that shifts as trades occur, which means large trades change the implied probability and cost dramatically. Thin liquidity also raises the chance of being unable to exit early when you want to. Always check pool depth and historical volume before sizing a trade.

Is insurance or protection available for DeFi binary options trading?

For DeFi binary options, insurance or loss protection is not automatically provided. Some protocols maintain internal insurance pools or integrate with third-party coverage providers, but these protections are typically narrow and limited in scope. They are often subject to the protocol’s own capital constraints and narrow claim triggers. Insurance terms are frequently technical and highly conditional, with strict definitions, claim requirements, and approval processes. Relying on implicit promises of coverage is not a good idea. Assume you are responsible for all losses unless explicit, well-capitalised protection is documented.

Coverage, when available, often applies only to very specific events, such as certain smart contract failures, and excludes common risks like pricing errors, MEV effects, or oracle issues. When insurance is constrained by the size of the available capital, payouts can be partial or unavailable if losses are large or widespread.

How should I size positions and manage risk specifically for DeFi binaries?

Treat them as speculative, high-variance bets. Position sizes should be small relative to total capital, with session, daily, and weekly loss caps enforced. Because outcomes are binary and streaks of losses are probable, use conservative per-trade percentages and strict stop-loss equivalents (session caps or maximum consecutive losses) rather than relying on exit orders. Account for gas and slippage costs in sizing calculations. If you cannot accept the possibility of rapid, total loss of your stake, do not participate.

How do tax and record keeping work?

Blockchains provide transaction history, but tax rules vary by country, answering this question is not possible without knowing the applicable jurisdiction. Generally speaking, DeFi settlements produce taxable events and you need to track realized gains/losses, timestamps, and local currency equivalent at time of event. Many jurisdictions require reporting of crypto income as capital gains. Keep detailed records and consult a tax professional familiar with crypto for compliance.

Examples of DeFi protocols and platforms that support binary options on-chain:

  • InjectiveThis is a a blockchain ecosystem with native support for DeFi binary options markets, allowing developers to build or trade binary-style outcomes using smart contracts and decentralized infrastructure.
  • Thales ProtocolThis is a decentralized protocol specifically designed for binary options trading on Ethereum, enabling users to create and trade markets where outcomes resolve to yes or no.
  • BinaryX
    This protocol focus on sports, political, or other event-based binary outcomes, integrating real-time data feeds for resolution.
  • Augur (prediction markets)
    While primarily a prediction market platform rather than a pure binary options platform, Augur lets users create and trade event outcomes that function very similarly to binary options contracts.

Derivatives

Contributor Image
Written By
Contributor Image
Written By
William Berg
William Berg is a legal expert with a focus on securities law and a long track record in the trading industry.
Contributor Image
Edited By
Contributor Image
Edited By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Updated

Financial derivatives are financial contracts whose value depends on an underlying asset or product (e.g. a stock index). They exist to transfer, redistribute or assume risk, and they also facilitate price discovery and allow exposure to assets without holding them directly. Examples of well-known and heavily utilized derivatives are forwards, futures, options and swaps.

Derivatives can be found on both exchanges and in over-the-counter markets, supported by clearing arrangements and regulatory regimes that aim to reduce counterparty and systemic risk. That said, derivatives are complex, and some of them automatically involves margin trading and/or leverage.

How derivatives work

A derivative is a contractual claim where the payoff is linked to the price or performance of something else, e.g. a commodity, equity, bond, interest rate, currency, or index. Examples of less conventional underlyings are weather and credit events.

The contract specifies the terms, e.g. price, quantity, dates and settlement method. It can be structured so that both parties have obligations (as it is with forwards and futures) or leave one of the parties free to make up their mind later (options contracts work this way).

Because the contract’s value derives from the underlying, derivatives can be used to replicate exposures that would otherwise require buying or selling the underlying asset itself. It important to understand the nature of the contract, however, because there is never any guarantee that the value will mimic the movements of the underlying exactly.

derivatives

Four examples of common derivatives and how they differ from each other

  • Forwards are private, bespoke agreements to exchange an asset at a future date for a price set today. They are typically traded over-the-counter (OTC) and are binding for both parties.
  • Futures are highly standardized versions of forwards. They are traded on exchanges with daily margining, which reduces counterparty risks. Just like forwards, they are binding for both parties.
  • Options give the holder the right, but not the obligation, to buy (call option) or sell (put option) the underlying at a pre-determined price (strike price). Options are available both on-exchange and OTC.
  • Swaps are agreements to exchange cash flows (commonly interest rate or currency payments) over time. They are powerful tools for managing long-dated exposures.

Forwards

Forwards are bespoke bilateral contracts to buy or sell an underlying at a pre-agreed price on a future date. Because they are customized, they can match odd maturities, non-standard quantities, and settlement conventions required by a corporate hedge. This flexibility comes at the cost of bilateral credit exposure to the other party unless collateral or central clearing arrangements are layered on.

A widely used variant in FX markets is the non-deliverable forward (NDF), which settles the difference in a hard currency rather than causing physical exchange of the currencies. It is useful where onshore convertibility is restricted.

Commodity forwards may specify physical delivery terms, storage obligations, and quality grades, so legal and operational detail matters. Pricing is usually a simple carry/arbitrage relation plus credit adjustment, but valuation can require careful credit and funding adjustments when the counterparty is not perfectly trustworthy.

Futures

Futures are similar to forwards, but futures are highly standardized and exchange-traded. The high degree of standardization means they are highly suitable for exchange-trading. The contracts trade on central limit order books, margins are posted and variation margin is exchanged daily, and a clearing house steps into the middle reducing bilateral exposure. Futures exist for things such as commodities, interest rates, equity indices, and currency exchange rates. The key differences versus forwards are liquidity and transparency on one hand, and less tailoring on the other. You give up bespoke features but gain central counterparty protection and usually better, more predictable exit conditions.

Some exchanges have begun to offer smaller contract sizes (mini and micro futures contracts) to broaden retail access to futures trading.

Options (vanilla and exotic)

Options give a holder the right, but not the obligation, to buy (call option) or sell (put option) an asset at a pre-determined price (the strike price).

Plain call and put options are known as vanilla options, and they are available both over-the-counter (OTC) and on exchanges. The most common exercise types are European-style, American-style, and Bermuda-style. European-style options can be exercised only at expiration, while American-style options can be exercised at any time up to and including expiration. Bermuda-style options can be exercised on specific predetermined dates between inception and expiration. These different exercise styles affect pricing, flexibility, and risk management, but not whether the option is considered vanilla or not.

Note: The term “vanilla option” has nothing to do with vanilla beans. The connection is purely metaphorical. In everyday English, vanilla is used to mean plain, standard, or basic, as in “vanilla software” or “vanilla ice cream.” Finance adopted this usage to describe basic put options and call options.

If an option is not vanilla, it is exotic. This category includes a lot of different options, e.g. barrier options that activate or extinguish at a barrier level, Asian options where the payoff depends on an average price, lookback options that reference the optimal past price, and compound options that are options on options. Exotics can introduce path-dependence, discontinuities, and additional state variables, so pricing typically needs specialized models and numerical methods. Exotic options are usually customized OTC contracts traded only between dealers, with a minimal or non-existing secondary market.

Swaps

Swaps are packages of cashflow exchanges structured to transform exposures. The most common is the plain-vanilla interest rate swap where one party pays fixed and receives floating interest. Currency swaps exchange principal and interest in different currencies, and can be used to obtain foreign currency funding. Total return swaps transfer the economic return of an asset (price change plus income) without transferring legal ownership, which can be useful for leverage or synthetic exposure.

Swaps are mostly OTC. They can be cleared through a Central Counterparty (Clearing House) if standardised, but long-dated bespoke swaps retain bilateral credit dimensions. Valuation depends on yield curves, credit spreads, collateral, and close-out conventions. It is important to understand the operational protocols (ISDA, CSA).

Examples of other derivatives

Swaptions, caps, floors, and collars

These are option-like overlays on interest rate or other cashflows. A swaption grants the right to enter a swap. Caps and floors provide ceilings and floors on floating rates, and they are often used to limit interest cost volatility. Collars combine caps and floors to create a bounded rate exposure, and are frequently used by corporations to manage borrowing costs.

Swaptions, caps, floors, and collars are intermediate in complexity. Their payoff structures are comparatively simply, but their valuation still requires forward curves and volatility inputs, and they interact directly with collateral and termination clauses.

Credit derivatives (CDS and related instruments)

Credit derivatives transfer credit risk from one party to another.

The credit default swap (CDS) is the archetype. The protection buyer pays periodic premiums to a protection seller who compensates the buyer if a pre-defined credit event occurs.

Variations include credit linked notes, total return swaps referencing credit assets, and basket or index CDS that reference a portfolio of credits.

Credit derivatives introduce counterparty concentration issues and require careful definition of credit events and settlement rules. During stress periods valuation and deliverability can be highly non-linear.

Contracts for Difference (CFDs)

Contracts for Difference (CFDs) are instruments that replicate the economic exposure to an underlying without transferring ownership. The dealer quotes the price, and the position is typically bilateral and OTC. CFDs are leveraged, marginable, and dependent on dealer credit.

CFDs are widely used by retail traders for equities, indices, forex, and commodities, and often carry financing charges for leveraged exposure. Their regulatory treatment varies by jurisdiction, especially when it comes to selling them to retail clients.

Why individuals, firms, and institutions use derivatives

Uses fall into three broad categories that sometimes overlap in practice, and understanding these three categories will help us understand why why derivatives have become so deeply embedded in corporate risk management and in the strategies of professional investors.

  • Hedging is used to reduce or transfer unwanted risk exposures. Firms and investors can for instance do multinational hedging through foreign currency receipts, and a pension fund might want to lock-in interest rate risk.
  • Speculation is when market participants take directional or volatility positions to seek profit. Many derivatives are leveraged, which means that even modest moves in the underlying can produce large gains or losses.
  • Arbitrage and other relative-value strategies are used by traders who exploit price differences between related instruments or between cash and derivative markets, which in turn connects prices and improves market efficiency.

For corporate and institutional investors looking to hedge, the main question is usually whether a derivative accurately transfers the exposure intended, at an acceptable cost, and with clear credit and settlement arrangements. For professional speculative traders, the question is whether the leverage and liquidity profile fit the firm’s risk limits and capital. For retail participants, complexity, leverage and counterparty choice matter, and listed derivatives traded on well-regulated venues generally offer greater transparency and complaint routes than bespoke OTC contracts.

Exchange-traded derivatives versus OTC markets

Two key distinctions between exchange-traded derivatives and OTC markets are where contracts are traded and how the counterparty relationship is managed. Exchange-traded derivatives (e.g. listed futures and listed options) are standardized, have transparent price discovery, and are centrally cleared. This reduces bilateral credit exposures and makes market access straightforward. Over-the-counter (OTC) derivatives (e.g. forwards, bespoke options, and non-listed swaps) are customizable and can match a specific hedge, but they expose parties to bilateral credit risk unless they are centrally cleared

or otherwise collateralize.

Market infrastructure and the role of central counterparties

Large portions of derivatives markets are supported by central counterparties (CCPs) that interpose themselves between buyer and seller and manage default risk through margining, default funds and other safeguards. By replacing a web of bilateral exposures with a hub of exposures to a CCP, central clearing reduces bilateral counterparty risk and creates netting efficiencies, but it also concentrates risk and creates a set of entities that are systemically important and therefore subject to close regulatory oversight. Well-designed clearing and settlement arrangements materially change the risk profile of trading, but do not remove market or liquidity risk.

Pricing

Pricing a derivative requires a model for the underlying’s future behavior and for the contractual payoff. Simple contracts (e.g. plain-vanilla futures) are priced using cost-of-carry or arbitrage relationships, while options pricing typically requires stochastic models of volatility and interest rates (Black-Scholes and its extensions are well known examples). Swaps and structured products can require yield-curve construction, credit spreads, and simulation of path-dependent payoffs. Model risk, parameter uncertainty (especially volatility), and assumptions about liquidity all affect valuation, and mismatches between model assumptions and reality are frequent sources of loss.

Risks — market, counterparty, liquidity, operational and legal, and systemic

  • Market risk: The underlying price moves against a position (and leverage magnifies losses).
  • Counterparty risk: The other party fails to perform their obligation. OTC trades without adequate collateral or clearing are especially risky.
  • Liquidity risk: Positions cannot be closed or hedged without significant cost in stressed markets where liquidity has dropped.
  • Operational and legal risk: Documentation errors, settlement failures, and ambiguous contract terms.
  • Systemic risk: Interconnected exposures and concentrations (for example through CCPs or large dealers) can propagate shocks across markets.

Regulation, reporting and market transparency

Since the financial crisis or 2008-2009, authorities have focused on pushing standardized, liquid derivatives into central clearing, improving trade reporting and reducing opaque bilateral exposures. Reporting regimes and margin rules for uncleared OTC derivatives have been strengthened, and many jurisdictions require registration or authorization of dealers and CCPs. These rules aim to increase transparency and resilience, but compliance creates costs and operational burdens for market participants.

How to trade derivatives

Do your homework

Before you start derivatives trading, it is important that you understand how it works and how to manage risk properly. Derivatives trading can differ a lot from non-derivatives, and you need to create a trading strategy and risk-management routines that reflects this. Simply jumping into derivatives trading based on a hunch and expect to learn the ropes playing fast and loose with real money is rarely a good idea. With the sink-or-swim approach, most novice retail traders sink, and they sink fast.

Trading derivatives is a procedural activity that combines market selection, legal and operational setup, disciplined trade design, and active risk controls. You need to learn how to pick an instrument that matches your objective, ensure the counterparty and clearing arrangements are appropriate, set margin and financing plans, define precise entry and exit rules, and keep records and post-trade checks. Done correctly it is a repeatable, auditable activity. Done poorly it quickly becomes a leverage-driven loss machine.

Derivatives are contracts whose value depends on another asset, and that makes them powerful but also capable of creating asymmetric outcomes and cascading obligations when markets move. Before trading, it is very important to understand the product mechanics (including things such as payoff, settlement, and expiry), the market microstructure (where and how orders execute), and the legal/operational framework (clearing, margin, close-out, etc.). Education resources from exchanges and industry bodies are practical first stops, because they explain contract specs and clearing rules in plain terms. Treat those materials as required reading, not optional.

Choose the right instrument for the objective

Match tool to task. If your goal is short-term directional exposure with defined downside, listed options or futures may be sensible. If you need bespoke timing, currency or quantity, an OTC forward or swap can match requirements better, at the cost of bilateral credit exposure and extra documentation. If you want simple indexed exposure with central counterparty protection, trade exchange futures or listed options are good candidates. Each choice can alter things such as margin needs, liquidity, and dispute routes, so the instrument selection should follow a clear, written rationale that links the intended economic exposure to contract terms and to how you will manage margin calls.

The practical differences across the different available derivatives and trading venues reduce to a handful of tradeoffs. Standardization and exchange listing give transparency, liquidity and central counterparty protection, but limit flexibility for contract terms. OTC derivatives, including bespoke products, give precision in matching exposures, at the cost of bilateral credit and operational complexities. Simpler payoffs (forwards, futures, vanilla options) allow more robust hedging and price discovery, while path-dependent or multi-factor payoffs (exotics, structured notes) raise model risk and hedging cost. Credit, legal and settlement conventions matter as much as the mathematical form. ISDA terms, collateral agreements, margining rules, and close-out provisions materially change valuation and risk. Accessibility is another important difference. Some instruments are effectively out of reach for ordinary retail traders due to factors such as size, documentation requirements, or regulatory thresholds, while others are available to retail accounts albeit sometimes with restricted leverage or disclosure.

Build a trading plan and risk framework

Before placing a trade write the plan, and make sure it includes instrument, direction, size, entry trigger, stop and/or hedging rules, expected holding period, financing cost estimate, and scenario P&L under key moves. Define maximum portfolio-level exposures (delta notional, vega notional, duration, credit line usage) and daily loss limits. Use position-sizing rules tied to available margin and to a stress loss tolerance rather than to notional size alone. The plan should be simple enough to be executable in a stressed market.

Select a counterparty or broker

For exchange-traded products, focus on regulated brokers that provide direct market access to the exchange and to the relevant clearing house. Verify the broker’s license, membership, clearing arrangements, and default procedures.

For OTC instruments, insist on a signed ISDA master agreement, a credit support annex (CSA) for collateral rules, and a clear schedule for margin computation and dispute resolution. Confirm which central counterparty, if any, will clear the trade and what the margin model is. For uncleared trades, verify the initial and variation margin mechanics and eligible collateral.

Account setup

Open the account type or types required by the product. A margin account for futures and options, a cleared account for CCP-cleared OTC trades, or a bilateral trading arrangement for bespoke swaps. Depending on jurisdiction and broker policy, you may need to pass trading-level checks and approvals that gate access to more complex strategies (e.g., uncovered options).

Capital planning

Calculate the worst-case margin funding you might need under reasonable stress scenarios and ensure capital is available to meet variation margin calls intraday. Funding plans should include contingency sources (collateral, credit lines or pre-positioned cash) and, for firms, a governance sign-off that specifies who can post or recall margin. Regulatory margin rules for uncleared derivatives also mandate specific initial and variation margin practices. Treat those as binding constraints on strategy sizing.

Execution mechanics and order types

Learn the exchange-specific tick sizes, contract months, and delivery/settlement conventions. Use limit and stop-limit orders (especially if liquidity is thin), and make sure you understand slippage and how it affects a leveraged position. For OTC fills, use electronic matching venues or request written confirmations and time-stamped trade tickets. If you use algorithmic execution, backtest against realistic market conditions and monitor implementation shortfall. For options, be mindful of legging risk when executing multi-leg strategies: partial fills on different legs create unintended directional exposure. Execution quality matters as much as strategy choice because a margin call can be triggered by execution slippage in a fast market.

Margin, collateral and funding management

Track initial margin and variation margin separately. Initial margin secures potential future exposure and variation margin covers mark-to-market changes. For centrally cleared products, margin can be substantial and is recalculated daily or even intraday. For OTC products, margining is contract-specific and subject to the applicable CSA terms. Choose eligible collateral carefully and watch haircuts and concentration limits. Haircuts are percentage reductions applied to the market value of collateral to account for risk, and a haircut will reduce the value of collateral that can be credited toward margin.

Model margin requirements under plausible stress scenarios (price moves, volatility spikes) and maintain a liquidity buffer so you can meet calls without forced liquidation. Funding friction (conversion fees, settlement delays, minimum transfer amounts) can make small portfolios fragile, so build operational processes (who transfers collateral, cut-off times, settlement instructions) and test them.

Hedging and trade management

Actively manage exposures. Hedging can be discrete (offsetting futures) or dynamic (delta hedging options), but both require discipline and attention. Rebalance hedges when market conditions or model inputs change materially. Do not rely on idealized model behavior in thin markets. For options, monitor Greeks (delta, gamma, vega, theta) and funding costs. For swaps, monitor curve moves and basis risk.

Keep a written decision log for hedge adjustments that links the change to a measurable trigger (e.g., delta crosses threshold, volatility > X). Without disciplined hedge rules small model errors compound into large P&L swings.

Post-trade operations, reconciliation and reporting

Confirm trades promptly, reconcile trade tickets to broker and clearing house records, and verify margin and cash movements daily. Discrepancies must be escalated immediately to avoid settlement failures. Maintain audit-ready records, including trade confirmations, intraday P&L runs, margin call history, and correspondence with counterparties. For regulated entities, comply with trade reporting regimes (exchange or trade repositories) and retain documentation per local rules. Poor post-trade controls are a frequent cause of operational loss and regulatory action.

Stress testing and exit planning

Simulate realistic stress scenarios, including large price moves, liquidity evaporation, and counterparty default. For each strategy define exit protocols (whether to hedge, to reduce size, or to transfer positions). Plan for unlikely but plausible events, such as inability to post margin, CCP default procedures, or legal disputes over close-out netting. Practice the plans, because you need to be able to actually follow them under stress.

Costs, taxes and accounting

Account for explicit costs (commissions, exchange fees, clearing fees, etc) and implicit costs (bid/ask spreads, slippage, financing rates, and so on). For options, include the cost of theta decay and implied volatility moves. For futures, include financing and rollover if you maintain exposure across expiries.

Understand tax treatment in your jurisdiction. Expert advice is a good idea to avoid problems down the road. Gains may be capital or ordinary income depending on the circumstances, and some jurisdictions treat derivatives differently depending on contract form.

Reconcile mark-to-market accounting, collateral accounting and tax reporting with your accountant or controller so that realized and unrealized P&L are treated consistently. Failure to account for the full cost of carry and tax drag often makes apparently profitable strategies unprofitable.

Common mistakes and how to avoid them

When we look at trading failures, we often see a handful of mistakes repeating over and over, including underestimating margin, ignoring clearing and legal terms, using inadequate execution procedures, over-relying on theoretical models without stress testing, and failing to document trade rationale.

Avoid these common pitfalls by insisting on practical pre-trade checks (documented strategy, margin funding plan, execution protocol), and by making post-trade reconciliation and daily P&L mandatory. Treat model outputs as inputs to decisions, not as substitutes for operational and governance processes. Simple controls and conservative sizing prevent a single bad move from triggering a catastrophic chain of events.

A common beginner mistake is to start too big, especially if a strategy has worked out really well in simulations. To avoid repeating this mistake, make sure you start small, and do not scale too quickly. Use exchange education tools and simulators to learn contract behavior, and test execution with small, real money trades that you can afford to lose. Build templates for trade tickets, margin forecasts, and post-trade reconciliation so that scaling up is not an afterthought. Document everything (trade rationale, approvals, the sources of funding, etc) so that every trade can be reconstructed and reviewed in an audit.

If trading OTC, engage legal counsel early to negotiate ISDA terms and a CSA. Do not rely on standard sales material.

Derivatives are fundamental tools in modern finance. They are powerful and necessary for risk management, but also able to amplify losses and create complex interconnections. Their legitimacy rests on clearly defined contracts, market infrastructure (exchanges, CCPs, custodians, etc), and a regulatory framework that enforces transparency and margining. Anyone dealing with derivatives must respect model risk, counterparty risk and liquidity risk, and should maintain strict operational controls and records. When used with appropriate governance, derivatives serve useful economic purposes, but when used carelessly, they are known to produce rapid, concentrated losses.

Examples of derivatives exchanges around the world

North America

The United States is home to several of the world´s largest derivatives exchange, including the CME Group (Chicago Mercantile Exchange & Chicago Board of Trade), the CBOE (Chicago Board Options Exchange), and ICE (Intercontinental Exchange).

The CME Group (Chicago Mercantile Exchange & Chicago Board of Trade) is chiefly focused on futures and options on futures, and the underlyings are usually commodities, forex, interest rates, or equity indices. The CBOE (Chicago Board Options Exchange) is more focused on options, especially options based on stocks and indices. This exchange created the famous VIX volatility index, which is now considered a key measure of market fear.

Headquartered in Atlanta, Georgia, USA, the Intercontinental Exchange (ICE) is a global exchange network which has become especially strong in energy and agricultural commodities, but also financial derivatives such as interest rate futures, equity index futures, and currency futures. After its creation in 2000, ICE grew rapidly by acquiring established exchanges, and it now operate both exchanges and clearing houses in North America, Europe, and Asia. Since 2013, ICE has also been the owner of the famous New York Stock Exchange (NYSE).

The derivatives exchanges in Canada and Mexico pales in comparison with the size of the main derivatives exchange in the U.S., but they do exist. The largest derivatives exchange in Canada is the Montréal Exchange (MX), which is the country’s principal marketplace for trading derivatives such as futures and options on equities, indices, currencies, interest rates, and ETFs. It is owned by TMX Group, the same company that owns the Toronto Stock Exchange. MX’s clearing and risk management functions are handled by its subsidiary, the Canadian Derivatives Clearing Corporation (CDCC).

The largest derivatives exchange in Mexico is the Mercado Mexicano de Derivados (MexDer). Based in the capital city, it is a part of the BMV Group (Bolsa Mexicana de Valores). MexDer is the leading exchange for derivatives in Mexico and also one of the main such venues in all of Latin America. It provides transparent, centralized trading and clearing via its clearinghouse Asigna, supporting risk management and settlement for market participants. Note: Although MexDer exists, a large portion of derivatives activity in Mexico overall still takes place OTC.

Europe

One of the largest derivatives exchanges in Europe is Eurex in Germany/Switzerland. This exchange focuses on equity index and interest rate derivatives. When it comes to derivatives based on energy commodities, agricultural commodities, or financial products, ICE Futures Europe in London is major player. For derivatives based on base metals such as copper, aluminum, and zinc, the dominant actor is the London Metal Exchange (LME), an old exchange with roots going back to 1877. LME contracts are linked to actual warehouses worldwide, so traders can settle contracts with physical metal delivery if needed. LME has a global reach and prices established here are widely used as global benchmarks for base metals. The LME prompt date system allowing trading of contracts for almost any date up to 123 months (over 10 years) in the future, giving flexibility for hedgers. Since 2012, the LME has been owned by the Hong Kong Exchanges and Clearing (HKEX).

Asia-Pacific

Alongside North America and Europe, the Asia-Pacific region is home to some of the major derivatives exchanges in the world, including:

  • The NSE (National Stock Exchange of India). Derivatives based on equity, index, currency, and interest rates.
  • HKEX (Hong Kong Exchanges & Clearing). Derivatives based on equity, index, and commodities. SGX (Singapore Exchange). Known for its derivatives on Asian equity indices, commodities, and interest rates.
  • The OSE (Osaka Exchange). This is the main derivatives exchange in Japan, and offers a wide range of derivatives, including futures and options on stock indexes and other financial instruments.

FAQ: Questions and answers about derivatives

What are structured products?

In this context, structure products are financial products that bundle derivatives with debt or cash elements to create bespoke payoffs. This category includes things such as equity-linked notes, principal-protected notes, reverse convertibles, and similar constructions. Structured products can offer tailored payoff profiles for investors with specific views or yield objectives. Their market value depends on the embedded derivatives’ pricing, issuer creditworthiness, and sometimes opaque fees, so careful disclosure and valuation transparency are crucial.

What are warrants?

Warrants are firm-issued long-dated options that entitle holders to buy equity at a strike price. They trade on exchanges but embed issuer credit risk.

Is it true that the weather can be an underlying for derivatives?

Yes, derivatives can be based on a wide range of things, including specific weather events. Beyond financial underlyings, there are derivatives that reference commodity prices, freight, emissions, and even weather indices (temperature, rainfall, snowfall, etc). These instruments often reflect the hedging needs of producers, service providers, consumers and utilities. They can be physically settled or cash settled against a published index.

Niche underlyings amplify operational complexity. Defining the reference index, determining delivery logistics, and ensuring that the hedge actually offsets the economic exposure are all non-trivial aspects of the deal.

Can I use derivatives to speculate on cryptocurrency exchange rates?

Yes. Derivatives referencing cryptocurrencies and tokenised assets have become common, and the selection now includes things such as perpetual swaps, futures, and options based on crypto assets. There are even structured products available that reference baskets of tokens. These instruments make it possible to speculate on crypto without ever owning any crypto. They combine traditional derivative mechanics with idiosyncratic risks of custody, exchange credit, and sometimes extreme volatility. Their legal and regulatory status varies greatly depending on the jurisdiction, and clearing options remain limited for many crypto derivatives.

Can retail traders use derivatives?

Yes, retail traders can trade derivatives, but what they can trade and what the requirements are depends on the type of derivative, jurisdiction, and broker rules. A common starting point for retail traders are exchange-traded derivatives, which tend to be the most accessible from a practical standpoint, and least restricted by legislators. This category of derivatives includes instruments such as exchange-traded vanilla options and exchange-traded futures. Both are available with a wide range of underlyings and are sufficient for the needs of a majority of all retail derivative traders. To make them more accessible, some brokers are now offering mini and micro exchange-traded futures and options. To trade exchange-traded futures or options, you need a suitable broker and a margin account. You can expect to be subjected to a suitability check before you are approved for derivatives trading.

Contracts for Difference (CFD) is a type of derivative that has become very popular among retail traders around the world, but retail CFDs are banned in some jurisdictions, including the United States, Belgium, and India. In several other jurisdictions, legislators and financial authorities have created special rules to better protect retail traders from the negative sides of CFDs trading, especially when it comes to leverage. The CFDs offered to retail traders from online trading platforms are typically not exchange-traded, or even OTC traded on some type of marketplace. Instead, you broker is also your counterpart in each trade. You and your broker are essentially betting against each other, and this automatically creates a conflict of interest that needs to be managed well. Serious CFD brokers typically hedge their exposure to reduce the conflict. Appropriate financial authority supervision and trader protection rules that actually have teeth are other important components when it comes to handling this conflict of interest.

Structured products are sometimes made available to retail clients, but special approval can be required.

Examples of derivatives that the typical retail trader will not be able to trade are bilateral OTC derivatives (e.g. interest rate swaps), products requiring ISDA + CSA agreements, and trades with custom margining or collateral negotiation. These types of products are the domain of institutional clients.

What is ISDA?

Most derivatives around the world use the ISDA Master Agreement, which defines things like payments, defaults, and what happens if a party fails. ISDA stands for the International Swaps and Derivatives Association. ISDA helps reduce legal uncertainty and systemic risk by making contracts consistent across countries, and the organization works closely with regulators and policymakers on derivatives regulation. Without widely accepted standardization, banks and financial institutions would have to negotiate separate legal terms for every derivatives deal, which would be slow, risky, and expensive.

What is a barrier option?

A barrier option is a type of exotic option where the payoff depends on whether the underlying asset’s price reaches (or “touches”) a specific barrier level during the option’s life. A barrier option may activate or disappear if the barrier is crossed, depending on the type of barrier option. If it is a knock-in option, it becomes active only if the underlying hits the barrier. If it is a knock-out option, it ceases to exist if the underlying hits the barrier.

Both “up” and “down” barrier options exist. For an “up” barrier option, the barrier is above the initial price of the underlying asset. For a “down” barrier option, the barrier is below.

Up-and-in = Option starts only if price rises to the barrier.

Up-and-out = Option is canceled if price rises to the barrier.

Down-and-in = Option starts only if price falls to the barrier.

Down-and-out = Option is canceled if price falls to the barrier.

Traders use barriers options due to a variety of reasons. Knock-out options tend to cost less to purchase compare to a corresponding vanilla option, since a knock-out option can disappear. For hedging purposes, barrier options can be used to tailor protection to specific price levels.

Barrier options are more complex than vanilla options. The pricing is sensitive not just to volatility and time to expiration, but also to barrier proximity. Barrier options are therefore not priced in the same way as vanilla options and their Greeks differ, which is important to take into account when you develop your strategy. Barrier options are path-dependent, meaning their value depends not just on the final price of the underlying, but on whether the barrier was touched during the option’s life.

What is an Asian option?

With an Asian option (Asian-style option), the payoff depends on the average price of the underlying asset (like a stock, index, or commodity) over a certain period of time, rather than just the price at one specific moment.

It is important to understand which type of Asian option you are using, because the average can be calculated in different ways. The most common way is arithmetic average, but geometric average also exist. Also, for some Asian options, the price over the entire entire life of the option goes into the calculation, and for others, another pre-specified window is used, e.g. the final three months.

Asian options are handy in markets where prices are known to be volatile or easily manipulated near expiration. They are commonly based on energy commodities, metal commodities, or forex.

Asian options are called Asian for historical reasons. They were first widely traded and developed in Asian financial markets, more specifically in Japan, Hong Kong, and Singapore. In the 1980s, traders in these markets frequently used averaging-based options, particularly for commodities and currencies, because averaging helped reduce price manipulation and extreme volatility near expiration. When these products later spread to European and U.S. markets, traders informally referred to them as “Asian-style options”, and the name stuck.

What is a lookback option?

With a lookback option, the payoff depends on the best (most favorable) price of the underlying asset over a certain period of time. Instead of caring only about the price at expiration, a lookback option lets the holder “look back” over the option’s life and use the maximum or minimum price that occurred. The idea is to remove the risk of bad timing.

With a fixed-strike lookback option, the strike price is fixed and the payoff depends on the best observed price. With a floating lookback option, the strike price is not determined until expiration, and is the same as best price observed.

Lookback options tend to be much more expensive than vanilla options, but can be worth their high premium for market participants who need to hedge when timing is uncertain and/or markets are highly volatile. Lookback options are also included in certain structured products.

What is a compound option?

A compound option is an option on another option. It gives you the right to buy (call compound option) or sell (put compound option) a different option at the predetermined strike price.

There are four standard types of compound options, based on call/put combinations:

  • Call on a Call (CoC) gives you the right to buy a specific call option
  • Put on a Call (PoC) gives you the right to sell a specific call option
  • Call on a Put (CoP) gives you the right to buy a specific put option
  • Put on a Put (PoP) gives you the right to sell a specific put option

The compound option creates a two-stage decision with layered risk and leverage, since there are two expiries and two strike prices to consider. The compound option is sensitive to volatility of volatility, and pricing is highly complex. With two time horizons, there are more Greeks to manage.

Buying a compound option is typically significantly cheaper than buying the underlying option directly. Compound options are commonly used when there is uncertainty about future hedging needs, e.g. in corporate finance. They are also used by traders who wish to make leveraged bets on volatility; they speculate on the option becoming valuable, not just the underlying asset. Compound options are especially common in forex markets and interest rate markets. A bank can for instance decide to use compound options to establish rate caps and floors, in situations where it is unsure if it will actually need the protection later.

As mentioned above, pricing a compound option is more complex than pricing a vanilla option. A

commonly used model is Geske´s Model (1979), which is a version of the Black-Scholes Model extended for compound options. Geske´s Model, which is the most well-known model for European-style compound options, extends the Black-Scholes formula to handle the fact that the underlying is itself an option. It uses bivariate normal distributions to account for the correlation between the underlying option price at the first expiry and the second option’s payoff. The key idea is that if
the first option expires at time T1 and gives the right to buy an option that expires at a later time T2, Geske’s formula calculates the present value of the expected payoff using risk-neutral probabilities and the joint distribution of the underlying asset at T1 and T2.

Best MT4 Binary Options Brokers For Swing Trading 2026

Contributor Image
Written By
Contributor Image
Written By
Christian Harris
Christian is an experienced swing trader with years actively trading stocks, futures, forex, and cryptocurrencies. He focuses on short- to medium-term strategies, combining technical analysis with disciplined risk management. His real-world trading experience helps him provide valuable perspectives for aspiring swing traders.
Contributor Image
Edited By
Contributor Image
Edited By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
William Berg
William Berg is a legal expert with a focus on securities law and a long track record in the trading industry.
Updated

If you already use MetaTrader 4 (MT4), you know it’s flexible, allows custom indicators, and many traders trust it. Using binary options on MT4 combines that familiarity with simpler payoff structures.

This guide, written by our trading experts, helps you choose a binary options broker that supports MT4 and swing trading, allowing you to focus on the features tailored for this overlap.

Binary Options & MT4 For Swing Trading

Binary options work on a simple idea: you predict whether a price will be above or below a set level when the option expires.

MT4 makes the process more practical for swing traders by providing access to real-time charts, technical indicators, and custom tools. You can study price patterns, set alerts, and track trends over several days—all within the same platform.

Swing traders use MT4 to identify broader market movements, rather than quick spikes. For example, you might notice a currency pair forming a steady uptrend and decide to place a ‘call’ option that expires in 48 hours.

MT4 helps you plan that trade with clean data and visual signals, while the binary setup keeps the outcome simple: win or lose, based on where the price ends.

Together, binary options and MT4 offer a balance between structure and flexibility—clear results with enough time to think through each trade.

MT4 platform at Pocket Option

Pocket Option’s MT4 platform offers solid charting tools and execution

Expiry Time Flexibility

Swing trades often last from a few hours up to a few days. That means your broker must support expiry times that match this range.

  • Look for brokers that allow daily expiries or multi-day expiries. If your only options are 60 seconds or 5 minutes, that won’t work for swings.
  • Some brokers label these as ‘end of day,’ ‘next day,’ or ‘2-day’ binaries.
  • Ensure your expiry times are precise (e.g., to the hour), not just ‘tomorrow,’ which could default to market close.

Example scenario: Suppose you spot a currency pair that looks bullish over the next day. You open a ‘call’ binary option that expires 24 hours later. If the broker only supports intraday expiries, you’d have to break your position into multiple smaller ones—harder to manage.

💡
If your chart setup indicates a move that may take two days, select an expiry that allows the trade sufficient time. Forcing a short expiry on a long setup typically yields unpredictable results.

Asset/Market Variety

Swing trades benefit from having a choice of markets (forex, indices, commodities, etc.). But you also need those assets available in binary format under MT4.

  • Check which underlying assets the broker offers in binary options mode on MT4.
  • Ensure you can view the price charts of those assets and apply your indicators in MT4.
  • For swing trading, more diversity helps—if one market is flat, you can switch to another.

Example scenario: You like trading AUD/USD and gold. If your broker supports gold binary options and AUD/USD binary options in the same MT4 account, you can move between them when trends shift.

Swing trading binary options on MT4 taught me that having a range of assets matters more than chasing a single market. Switching between currencies, indices, or commodities often makes the difference between a dry streak and steady opportunities.
author image
Christian Harris
Author

Indicator & Chart Tools

One reason to use MT4 is access to chart tools and indicators. For swing trading, you often rely on trend lines, moving averages, RSI, etc.

  • The broker must feed real or near-real price data into the MT4 charts that match the binary option’s underlying.
  • Indicators must reflect the same price data that the binary option uses. If there’s a mismatch, your entry signal may be wrong.
  • Be able to overlay your strategy tools: drawing tools, trend lines, and custom indicators.

Example scenario: You see a crossover of a 50 and 200 EMA on the MT4 chart, signaling an upcoming move. You want to act on the binary option tied to the same currency pair, knowing that the chart and the option move in tandem. If the broker’s option price is slightly offset, your strategy fails.

💡
Combine basic indicators, such as moving averages or RSI, with simple chart patterns. Swing trades work best when technical signals agree, not when you rely on one indicator alone.

Execution Reliability & Slippage Protection

Swing trades aren’t ultra-sensitive to millisecond delays, but you still need reliability. If the broker has poor execution or price jumps (slippage), your entry or exit may not align with your plan.

  • Check for brokers who guarantee no slippage (or minimal) on binary entries.
  • Look for servers with stable performance and reliable connection uptime.
  • Read user reviews (especially for swing traders) to see if others report mismatches between the MT4 chart and the option execution.

Example scenario: You observe a signal at 1.2000 on the EUR/USD pair. You place a ‘put’ option. If execution lands at 1.2005 due to slippage, the option may open less favorably. Over time, repeated slippages erode your edge.

In my experience, swing trading binary options on MT4, even with a high-probability setup, can lose its edge if the broker’s execution lags or slippage occurs. Consistent price alignment between the MT4 chart and trade entry is critical for accuracy.
author image
Christian Harris
Author

Transparency In Pricing & Payouts

Because binary options have fixed payouts, the exact ratio between what you risk and what you gain matters a lot for swing trades (which might only take a moderate size).

  • Confirm that the payout percentages are clearly displayed before placing trades.
  • Watch for hidden fees, commissions, or adjustments.
  • Check whether the broker adjusts the payout mid-trade due to volatility or other factors.

Example scenario: You might see a 70% payoff displayed for a 24-hour option. But if the broker tweaks it down after you place the trade because volatility spiked, your expected return changes. That undermines trust in your edge.

Risk Management Tools

Even though binary options are simpler, swing trades still need risk control:

  • Ability to limit total exposure (max number of open options).
  • Ability to cancel or reverse specific trades (if allowed) or ‘roll over’ expiry (if supported).
  • Clear display of potential loss versus gain before placing a trade.

Example scenario: You enter two swing binaries, but then new data suggests one looks weak. If your broker allows cancellation or reversal, you might be able to close early with minimal loss. Many binary options brokers don’t let you do that, so you must accept the full risk until expiry.

Demo Or Practice Mode

Especially for beginners, you want a demo account that mirrors real conditions for swing trades.

  • The demo should support the same expiry structures, assets, and MT4 setup.
  • If your demo has only short expiries, you won’t be able to test your swing strategies properly.
  • The demo should use realistic spreads, execution, and payouts.

💡
Keep a log of every swing trade: entry, expiry, and reason for taking it. Over time, you’ll spot which setups actually work for you and which ones just look good on the chart.

It’s worth verifying that the broker is legally authorized to offer binary options in your country. But more relevant:

  • The broker should clearly state how binary options are handled via MT4.
  • Terms and conditions should explain how expiries, payouts, execution, and data feed work.
  • If they treat binary options differently from other derivatives on MT4, that should be transparent.

Support & Documentation

Setting up binary options inside MT4 isn’t always trivial. Good support matters.

  • Tutorials or guides specific to setting up binary options on MT4.
  • A responsive support team familiar with both MT4 and binary options.
  • Examples or case studies showing how to use swing strategies with their MT4 binary plugin or module.

Cost Of Inactivity, Rollover, Or Expiry Mismatches

Even if a trade expires normally, you may incur costs:

  • Some brokers charge inactivity fees if you hold positions for more than a day.
  • Some may adjust the expiry timing if the market is closed (e.g., weekends, holidays).
  • Ensure the broker handles holidays, gaps, or non-trading sessions consistently and predictably.

Example scenario: You open a binary that’s supposed to expire in 48 hours. Due to the weekend, the broker may shift its expiry into a less favorable time window. That could distort your strategy outcome if you hadn’t planned for it.

Bottom Line

Choosing the best MT4 binary options broker for swing trading comes down to how well the platform fits your trading rhythm.

You need expiry times that last hours or days, reliable price data that matches your MT4 charts, and execution that doesn’t slip. Payouts and fees should be clear from the start, with no surprises.

A good broker also makes it easy to manage risk, test strategies in a realistic demo environment, and receive assistance when setting up MT4 for binary options.

In the end, the right broker supports your trades quietly and consistently—no hype, no gimmicks, just tools that work.

Best Swing Trading Brokers For Funded Accounts 2026

Contributor Image
Written By
Contributor Image
Written By
Christian Harris
Christian is an experienced swing trader with years actively trading stocks, futures, forex, and cryptocurrencies. He focuses on short- to medium-term strategies, combining technical analysis with disciplined risk management. His real-world trading experience helps him provide valuable perspectives for aspiring swing traders.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
William Berg
William Berg is a legal expert with a focus on securities law and a long track record in the trading industry.
Updated

Swing trading with a funded account differs from trading with your own money. The broker you use has to match the way funded programs work. If it doesn’t, you’ll run into limits that can eat into profits or break the rules of your program.

We’ve reviewed the best brokers that work with funded accounts and highlighted the ones that best fit swing trading.

Holding Trades Overnight

Swing traders typically need to keep trades open for several days, sometimes even weeks. Some brokers that work with funded programs don’t allow this. Others charge higher swap or rollover fees.

Before you choose, check:

  • Can you hold positions overnight without breaking rules?
  • Are there higher costs for long holds?
  • Does the program cut leverage for overnight trades?

💡
If overnight trades aren’t supported, the account may not work for swing trading.

Weekend Holding Rules

Some funded accounts force you to close positions before Friday’s market close. This eliminates many swing strategies because setups often require days to unfold.

Ask yourself:

  • Does the broker allow holding over the weekend?
  • Are there special restrictions, such as reduced lot sizes?
  • Is there a fee or penalty for leaving trades open?

💡
As a swing trader, you need the option to ride through weekends without breaking rules.

Leverage & Position Sizing

Swing trading relies less on extreme leverage than scalping. However, leverage still matters because funded accounts often have relatively small balances compared to their targets.

Check for:

  • Is leverage high enough to size trades without overexposing?
  • Does the program reduce leverage for specific pairs or during news events?
  • Are there minimum lot sizes that make risk control harder?

💡
Leverage rules should give enough room to trade safely, but not force oversized bets.

Spread & Swap Costs

Costs hit swing trading in two ways: spreads and swaps.

  • Spreads affect entries and exits.
  • Swaps matter when holding for days.

💡
A slight spread difference may not matter much for long holds, but a bad swap rate can eat up profit.

Compare:

  • Average spread on pairs you trade most.
  • Positive vs negative swaps. Some brokers flip them in a way that makes holding expensive.

Low costs keep trades flexible.

On funded accounts I’ve traded, spreads are manageable because entries aren’t as frequent in swing trading. The real drain comes from swaps—holding a position overnight with a negative rate can eat into profit faster than expected. Over the course of a week or two, those charges add up enough to change whether a setup is worth holding.
author image
Christian Harris
Author

Slippage & Execution

Execution speed is not just a problem for scalpers. Swing traders often set stop orders or enter around breakout levels. Slippage can cause entries to be pushed further away than planned.

Ask:

  • Does the broker maintain stable execution during volatile market conditions?
  • How wide is slippage during news or low liquidity?

💡
Even if you hold trades for days, a bad fill can change the setup.

Data Feeds & Chart Reliability

Swing trading depends on accurate chart history and clean price feeds. Funded accounts sometimes connect to brokers with odd feeds. A candle that appears differently between brokers can alter the entire setup.

Check:

  • Does the broker feed match widely used price data?
  • Are charts reliable when markets move fast?
  • Are there frequent disconnects?

You need charts you can trust to plan entries and exits.

Trading on MT5 WebTrader

MT5 WebTrader is an easy-to-use platform that runs in your browser

Program-Specific Broker Choice

Some funded account providers lock you into a specific broker. Others give you options. If you’re locked in, the choice is simpler—you work with what’s offered. But if you can choose, weigh the rules against your style.

Key questions:

  • Does the funding firm choose the broker, or can you link your own?
  • Do you get the exact account terms if you switch brokers inside the program?
  • Are demo and live feeds consistent?

💡
If the program is strict, you may have to adjust your strategy to fit the broker.

Risk Rules That Affect Swing Trades

Funded accounts have rules on daily loss, max drawdown, or news trading. Even if the broker supports swing trades, these rules can block you.

Check for:

  • Do daily loss limits reset if you hold trades overnight?
  • Is the floating drawdown counted against the daily loss?
  • Are there bans on holding through news events?

💡
A swing trade may last through multiple events, so the rules need to match that reality.

Instrument Access

Not every broker tied to a funded program offers the same pairs or markets. As a swing trader, you may prefer to trade majors, minors, commodities, or indices.

Look at:

  • Are the pairs you trade most available?
  • Do exotic pairs come with extreme costs that make swing trades unworkable?
  • Is the product list broad enough to find clean setups on a regular basis?

💡
A limited instrument list narrows your options and may force trades you’d rather skip.

Broker Stability & Support

Funded trading is already stressful due to its strict rules. A broker with unstable platforms or slow support exacerbates the issue.

Consider:

  • Does the trading platform crash during peak hours?
  • How fast does support respond if something breaks mid-trade?
  • Is there a clear record of payouts and withdrawals?

💡
Even if the rules fit swing trading, the broker still needs to be dependable.

Demo Vs Live Differences

Most funded accounts start with a demo evaluation. Then, if you pass, you move to live or simulated funded accounts. Sometimes, execution, spreads, or swaps change when you go live.

Think about:

  • Is execution the same between demo and live?
  • Do swap rates shift once you’re funded?
  • Are spreads consistent across phases?

💡
You want to avoid changing your strategy just because the account type switches.

Platform Choice

Some brokers only connect with MetaTrader 4 (MT4) or MetaTrader 5 (MT5). Others offer cTrader, TradingView, or proprietary platforms. Swing trading can work on any, but you may prefer one for charting or automation.

Check:

  • Is the platform stable for longer-term trades?
  • Can you backtest swing setups easily?
  • Do you trust the platform data for planning?

💡
The broker’s trading platform should support your workflow, not limit it.

Final Thoughts

The best broker for swing trading with a funded account isn’t about big promises or fancy features. It ultimately comes down to whether the broker aligns with your trading style and the rules of the funding program.

If you can hold trades overnight and through weekends, manage costs without spreads or swaps eating into profits, and rely on stable execution and data feeds, then the broker is likely a good fit. It also helps if the platform is stable and the account rules don’t hinder the way swing trades actually play out.

In the end, the right choice is the one that lets you trade the way you already trade—without forcing you to adjust your strategy just to fit the broker. That’s what makes a broker truly suitable for swing trading with a funded account.

Best Swing Trading Brokers For Cent Accounts 2026

Contributor Image
Written By
Contributor Image
Written By
Christian Harris
Christian is an experienced swing trader with years actively trading stocks, futures, forex, and cryptocurrencies. He focuses on short- to medium-term strategies, combining technical analysis with disciplined risk management. His real-world trading experience helps him provide valuable perspectives for aspiring swing traders.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Updated

A cent account makes it easier to start small, since your balance shows in cents and lets you manage risk with tiny steps. However, not every broker’s cent account is well-suited for swing trading.

Dig into our pick of the best swing trading brokers with cent accounts – tested by our experienced traders and industry experts.

How SwingTrading.com Chose The Top Cent Accounts

We selected the best cent accounts by first sorting brokers by their overall ratings, blending key swing trading data points, such as spreads, execution quality, and leverage options, with our team’s hands-on testing insights.

This combination of quantitative analysis and practical experience ensured our recommendations reflect both performance metrics and real-world usability.

What To Look For In A Cent Account

Swap & Overnight Costs

Swing traders almost always face overnight charges. Every time you roll a position past midnight, the broker applies a swap fee. Some pairs might even give you a small credit, but most of the time you’ll be paying.

On a cent account, these costs can look small at first, but they stack up quickly if you hold trades for a week or two. A strategy that looks profitable on paper can lose its edge once swaps are included.

What to look for:

  • A broker that posts clear daily swap rates.
  • Information on how rates are calculated.
  • Options for swap-free accounts, if available.

If the broker hides swap details or changes them often, it’s harder to plan swing trades with confidence.

I didn’t notice overnight charges on my account at first, but after holding forex trades for a week, the swaps added up and taught me to factor time into every plan.
author image
Christian Harris
Author

Execution Quality

Fast execution isn’t as critical for swing trading as it is for scalping—still, order quality matters. If a stop order doesn’t trigger where you planned, you could end up with a worse entry or a bigger loss.

On cent accounts, some brokers run trades on less expensive infrastructure, which can result in more re-quotes or slippage. Over a series of trades, this adds up.

What to look for:

  • A record of stable execution with minimal delays.
  • Limit and stop orders triggering correctly.
  • Few complaints about re-quotes.

Smooth execution won’t make or break every trade, but it keeps your strategy consistent.

Spreads & Commissions

Every trade starts with a cost: the spread. For swing trading, this isn’t as painful as for scalpers, since you aim for bigger targets. Still, wider spreads on cent accounts can reduce your profit margin.

Some brokers also add extra markups on cent accounts. You might see spreads double compared to their standard accounts.

What to look for:

  • Transparent spread tables for cent accounts.
  • Comparison with the broker’s standard account.
  • Commission-free trading that doesn’t come with inflated spreads.

💡
Lower spreads and commissions mean more room for your swing trades to breathe. Pay attention to both entry and exit costs, and compare spreads across different brokers before committing. Even small differences can add up over multiple trades

Position Size Flexibility

The biggest draw of a cent account is the ability to trade with very small lot sizes. This helps when you want to test swing setups without risking much. You can scale into trades slowly or manage risk with more precision.

What to look for:

  • Brokers that allow micro (0.01) or nano (0.001) lots.
  • Clear minimum trade sizes.
  • The ability to add or reduce positions in small steps.

The more flexible the trade size, the easier it is to practice good risk management.

Trading swings on a cent account taught me patience. The profits were tiny, but so were the mistakes—and that space to practice without fear was worth more than the cents themselves.
author image
Christian Harris
Author

Margin & Leverage

Swing trading means holding trades overnight, so margin is tied up for longer. The level of leverage on cent accounts affects how many trades you can keep open.

Too much leverage can be dangerous, but too little can limit you. A balanced level gives you flexibility without forcing you to over-commit.

What to look for:

  • Leverage levels that suit your style (not just the maximum advertised).
  • Margin call rules—when the broker starts to close trades.
  • Whether leverage differs between instruments.

A clear margin policy helps avoid nasty surprises when trades run longer than expected.

Trading with leverage on a cent account showed me both sides of the coin—the freedom to open more positions and the risk of watching them vanish just as quickly.
author image
Christian Harris
Author

Platform Stability

Swing traders don’t need advanced tools, but they do need a stable, reliable platform. Crashes or outages at the wrong time can block you from adjusting trades.

What to look for:

  • Access to MetaTrader 5, cTrader, TradingView, or another established platform on cent accounts.
  • A mobile app that works smoothly.
  • Basic charting tools for tracking support, resistance, and moving averages.

Even simple setups need clear charts and stable order handling.

Swing Trading oil on TradingView

TradingView stays stable for cent account trades, keeping charts and orders reliable

Instrument Range

Not every cent account offers the same instruments as a standard account. Sometimes, only a few forex pairs are available. If your swing strategy needs specific markets, check availability early.

What to look for:

  • Access to forex majors and minors.
  • Whether metals, indices, or commodities are offered in cent mode.
  • Swap and spread details for each instrument type.

The right mix of instruments lets you adapt to changing market conditions.

On my cent account, I realized the choice of instruments was limited—it pushed me to master a few pairs instead of chasing every market.
author image
Christian Harris
Author

Risk Management Tools

Swing trading is all about patience, but patience without risk control is risky. Stop losses, take profits, and trailing stops are essential.

What to look for:

  • Guaranteed support for stop-loss and take-profit orders.
  • Trailing stop functions that work on cent accounts.
  • Any limits on the number of orders or modifications allowed.

💡
Good tools let you manage risk even if you’re not at the screen every hour. Use stop-loss and take-profit orders, and consider trailing stops to lock in gains as a trade moves in your favor.

Deposits & Withdrawals

Most traders use cent accounts to start small. That means you need flexible funding options. If the broker sets high withdrawal minimums, it defeats the purpose.

What to look for:

  • Low minimum deposit and withdrawal amounts.
  • Clear fee structures for small transfers.
  • Reasonable processing times.

💡
Start with deposits you’re comfortable risking and practice withdrawing small profits regularly. This helps you stay disciplined, test strategies without stress, and avoid locking up money unnecessarily.

Broker Policy On Cent Accounts

Some brokers treat cent accounts as a secondary product, rather than a full trading option. They may restrict features, limit instruments, or raise spreads.

What to look for:

  • A cent account that works like a standard account in every way except balance size.
  • No restrictions on order types.
  • Consistent leverage and execution quality.

The goal is to trade, usually, just with smaller steps.

Final Thoughts

Swing trading with a cent account makes sense for many traders. It allows you to hold trades for days without risking much money, while still working in real market conditions.

However, not all cent accounts are the same. The details—swap costs, spreads, execution, margin rules, and platform stability—shape whether your trades succeed or not. A cent account is only helpful if the broker treats it fairly and provides the same quality as standard accounts.

Take the time to check these points before you choose. The best swing trading broker for cent accounts gives you space to practice, refine your strategy, and trade swing setups with confidence.

Best Swing Trading Brokers For Micro Accounts 2026

Contributor Image
Written By
Contributor Image
Written By
Christian Harris
Christian is an experienced swing trader with years actively trading stocks, futures, forex, and cryptocurrencies. He focuses on short- to medium-term strategies, combining technical analysis with disciplined risk management. His real-world trading experience helps him provide valuable perspectives for aspiring swing traders.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Updated

Micro accounts let you trade smaller lot sizes and limit risk while you learn or test strategies. But our tests show not every micro account broker is worth your time.

That’s why we’ve rounded up the best micro account brokers for swing traders.

How SwingTrading.com Chose The Top Micro Accounts

We identified the best micro accounts by ranking brokers based on overall ratings, then combining relevant trading data points, including spreads, trade execution, and account flexibility, with our team’s hands-on testing insights.

This balanced approach ensures our picks reflect both measurable performance and practical trading experience.

What To Look For In A Micro Trading Account

Trade Size Flexibility

The whole point of a micro account is trading in small sizes. Not all brokers let you do this properly. Check if the broker supports micro lots (0.01 lot). Some even allow nano lots (0.001 lot).

The smaller the lot, the more precise you can be with risk. This is especially useful in swing trading, where stop losses can be wide. Without small lot options, you’ll risk too much per trade.

For example, if your account has $200, trading a full lot isn’t possible. However, with micro lots, you can risk just $1 to $2 per trade. This lets you stay in the game longer while testing your system.

TopFX micro lot

You can trade at TopFX with positions starting from just 0.01 lots

Spreads & Costs

Swing traders don’t trade as often as scalpers, but costs still add up. Every spread and commission eats into profit.

Micro accounts usually come with wider spreads than standard accounts. Compare spreads across brokers, especially on the pairs or markets you want to trade. Even a few tenths of a pip matter if you plan to hold multiple trades at once.

Imagine you open three trades across different pairs, each held for a week. A wider spread on all three could take $5 to $10 off your profit. That’s meaningful when your account is small.

Swap & Overnight Fees

Because swing trades last days or weeks, swap charges matter. Swap is the fee or credit you pay for holding a trade overnight. Some pairs have positive swaps, but many don’t.

A small negative swap may not hurt much on a short hold, but over weeks, it stacks up. Always check how the broker handles swaps on micro accounts. Some brokers offer swap-free options, but read the fine print to see if other fees replace them.

For instance, if you hold EUR/USD short for 14 nights and the swap is –$0.10 per micro lot, that’s $1.40 gone. On a small account, it matters.

Using a micro account for swing trading showed me how costs quietly eat into gains. Even small spreads and overnight fees matter when you hold trades for several days. It forced me to plan each move carefully and focus on setups that really make sense, instead of chasing every signal.
author image
Christian Harris
Author

Order Execution Speed & Reliability

You won’t need split-second execution like a day trader. But you still need orders to fill at the price you set.

Swing traders often use pending orders, like buy stops or sell limits. If the broker delays execution or slips prices, it changes your risk.

Ensure the broker has a proven track record of consistent execution. This is especially key in fast-moving markets.

Platform & Tools

Swing traders need good charting. You’ll want to see daily, 4-hour, and weekly timeframes with clarity. A basic platform with limited charting capabilities makes analysis more challenging.

Look for brokers that offer solid charting tools. MetaTrader 4 (MT4), MetaTrader 5 (MT5), cTrader, or TradingView integrations are standard.

Also, check if you can use alerts, templates, or indicators you rely on. The platform should let you manage trades without friction.

Trading a micro account on cTrader

Test strategies on cTrader with small micro lot positions before scaling up

Risk Management Features

Swing trades last longer, so a broker with excellent risk management tools is critical. You need stop losses and take profits that actually trigger at your set levels.

Some brokers have slippage issues, even on stops. Others may not offer guaranteed stop-losses on micro accounts.

Make sure the broker lets you control your exits without hidden limits. Being able to adjust trade size down to the micro lot is most important.

Account Minimums & Funding

Micro accounts are meant for small deposits. Check the minimum deposit requirement. Some brokers advertise micro accounts, but then require high deposits to open one. Others allow starts for $5 or $10.

Funding methods for trading also matter globally. Not every trader can use the same payment systems. Confirm the broker accepts the deposit and withdrawal methods you can actually use.

Leverage Options

Swing trading often needs wider stops. That makes leverage a factor. High leverage lets you place trades without tying up your whole balance. But with a micro account, you also want to avoid overleveraging.

Check if the broker offers flexible leverage settings. Too low leverage can block trades. Too high leverage can tempt mistakes. The right broker gives you a choice.

Market Access

Not all brokers offer the same markets on micro accounts. Some limit instruments to major forex pairs only. Others extend micro trading to indices, commodities, or even crypto.

As a swing trader, you may want more than just EUR/USD. Wider access gives you flexibility. Before opening an account, confirm which instruments are actually tradeable in micro size.

Scaling Up

A micro account often serves as a stepping stone. You start small, build skill, then grow. It’s worth checking how easy it is to scale up with the same broker.

Can you switch to a standard account without hassle? Will trading conditions improve as your balance grows? A broker that supports growth saves you from moving accounts later.

Trading swing setups on a micro account taught me patience more than anything else. The profits looked tiny at first, but the small size kept me from blowing up when a trade went wrong. It’s not glamorous, but it’s the most honest way I found to learn how swings actually play out over days and weeks.
author image
Christian Harris
Author

Example Swing Trade Using A Micro Account

Let’s walk through a simple trade. Say you open a micro account with $250. You decide to trade EUR/USD.

  • Analysis: On the daily chart, you see the pair bouncing off support at 1.0800. You believe it will climb back to 1.1000 in the next two weeks.
  • Entry: You place a buy at 1.0820 with a stop loss at 1.0750 and a take profit at 1.1000.
  • Position size: You choose 1 micro lot (1,000 units). At this size, each pip is worth about $0.10.
  • Risk: Your stop loss is 70 pips below entry. That’s a risk of $7 (70 x $0.10). This equals less than 3% of your $250 account—reasonable for a swing trade.
  • Reward: If price hits 1.1000, that’s 180 pips of profit, or about $18. You’re risking $7 to make $18, which is a decent ratio.

Over the 10 days you hold the trade, you pay a total of –$1.20 in negative swap. Your trade closes at the target, giving you a net gain of $16.80. On a $250 account, that’s about a 6.7% return on one trade, without risking too much.

This example illustrates why micro accounts are beneficial. You manage risk in small dollar amounts, but still take meaningful trades. With larger positions, you could have risked too much on the same setup.

Bottom Line

Choosing the best broker for swing trading with a micro account isn’t about hype. It’s about the basics: trade size control, fair costs, stable platforms, and access to markets.

Micro accounts are meant to limit risk and give flexibility while you grow. Focus on the details that matter most to swing trading—overnight costs, lot sizes, and order reliability.

If a broker checks these boxes, you’ll have a smoother start and a setup that supports your trading style.

Best Commodity Brokers For Swing Trading 2026

Contributor Image
Written By
Contributor Image
Written By
Christian Harris
Christian is an experienced swing trader with years actively trading stocks, futures, forex, and cryptocurrencies. He focuses on short- to medium-term strategies, combining technical analysis with disciplined risk management. His real-world trading experience helps him provide valuable perspectives for aspiring swing traders.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Updated

Swing trading commodities is all about spotting short- to medium-term price movements and acting decisively. And I know from firsthand experience that the broker you use to do that through is vital.

We highlight the best commodity brokers for swing trading that give you the edge you need to navigate energy, metals, and agricultural markets with confidence.

How SwingTrading.com Chose The Top Brokers For Commodities

We identified the best brokers for commodities by analysing their range of markets (from gold and oil to softs and energies), spreads and fees, and contract types offered, then testing platforms directly to assess execution quality and trading experience.

By combining these quantitative checks with hands-on insights, we highlighted brokers that make commodity trading both accessible and cost-effective.

How To Choose A Commodity Broker For Swing Trading

  • Market access & instruments: The commodities a broker offers shape your trading opportunities and diversification. Access to metals, energy, and agricultural markets lets you act on global cycles, while understanding instruments—futures, CFDs, or physical contracts—helps manage leverage, costs, and risk.
  • Fees & costs: Trading costs directly impact profitability, particularly for leveraged, short-term trades. Brokers may charge commissions or embed costs in spreads, which can widen during volatility. Overnight positions may incur swap or rollover fees, and deposit, withdrawal, or inactivity charges can quietly erode gains. Awareness of these costs allows you to manage net returns efficiently.
  • Platform & tools: A broker’s platform dictates how effectively you can analyze and act on market movements. Platforms like MT4, MT5, and cTrader provide advanced charting, custom indicators, and automated trading tools—essential for timing swing entries and exits. Mobile apps and integrated fundamental data enable you to monitor and react to volatile commodity markets from anywhere.
  • Leverage & risk management: Leverage magnifies both gains and risks. Understanding margin requirements is critical, as falling below them can trigger margin calls or forced liquidations. Risk management tools like stop-loss orders and negative balance protection help limit losses in fast-moving commodity markets.
  • Order execution: Fast, reliable execution is vital for swing trading. Market execution fills orders at current prices, while instant execution locks in a quote before confirmation. Brokers offering multiple order types—market, limit, stop, and trailing stop—give you the flexibility to enter, exit, and manage positions strategically.
  • Account types & base currency: Account features affect leverage, fees, and trading scope. Choosing an account in your preferred currency can reduce conversion costs and simplify cost management.
  • Support & education: Strong customer support and educational resources are invaluable. Multi-channel assistance ensures timely help, while webinars, tutorials, and market analysis empower you to refine strategies and make informed decisions.
  • Regulation & safety: Regulated brokers provide transparency, segregated client funds, and capital adequacy safeguards. Many jurisdictions also offer investor protection schemes, giving you added security while navigating high-risk commodity markets.

With commodities, where overnight fees and execution speed can make or break a trade, the right broker feels less like a platform and more like a risk management tool.

After switching to a broker with tighter spreads and more reliable fills, I noticed that my setups started paying closer to what I’d planned on the chart.

author image
Christian Harris
Author

What Is Commodity Swing Trading?

Commodity swing trading involves targeting short- to medium-term price movements in markets such as oil, gold, or agricultural products, typically over several days to a few weeks.

Traders rely on technical analysis tools—like Fibonacci retracements, moving average crossovers, and momentum oscillators—to identify high-probability entry and exit points.

Beyond charts, successful swing traders factor in supply-demand imbalances, seasonal trends, and macroeconomic indicators such as inventory reports or currency shifts, allowing them to anticipate swings rather than react to them.

Risk management—position sizing, stop-loss placement, and volatility-adjusted targets—is critical to protect capital while exploiting these fleeting opportunities.

Trading commodity gold CFD through a chart from IG

Swing trading gold at IG with MACD, RSI, and defined risk/reward levels

Pros Of Commodity Swing Trading

  • Exploit short-term volatility: Commodity prices fluctuate in response to seasonal cycles, supply shocks, and shifts in demand. You can capture these moves using technical setups like trendline breaks, moving average crossovers, or Bollinger Band signals.
  • Flexible leverage & risk control: Margin trading allows you to scale positions with disciplined stop-losses and volatility-adjusted sizing, maximizing returns while managing risk.
  • Combine technical & fundamental edge: Swing trading lets you time trades with charts while factoring in inventory reports, weather, and geopolitical events, giving a practical edge over purely long-term strategies.

Cons Of Commodity Swing Trading

  • Market volatility can backfire: While swings create opportunities, sudden commodity shocks—like geopolitical crises or unexpected weather events—can trigger rapid losses if stops aren’t tight.
  • Requires constant monitoring: Swing trading demands regular chart checks, news tracking, and adjusting positions, which can be time-intensive compared to longer-term strategies.
  • Higher transaction costs: Frequent entries and exits can accumulate fees and spreads, eating into profits, especially in less liquid commodity markets.

The biggest lesson I’ve learned in swing trading commodities is that timing isn’t just about the chart—it’s about understanding the rhythm of the market itself. Oil reacts to headlines, gold to sentiment, and crops to seasons. Aligning setups with those cycles makes trades feel calculated, not random.
author image
Christian Harris
Author

Bottom Line

Choosing the right broker is crucial for commodity swing trading, as execution speed, market access, and reliable tools directly affect profitability.

The best commodity brokers for swing trading offer competitive fees, advanced charting and order management, responsive support, and access to multiple commodity markets.

With the right platform, you can efficiently capitalize on short- to medium-term price swings while managing risk with precision.

Best Swing Trading Brokers With Fixed Spreads 2026

Contributor Image
Written By
Contributor Image
Written By
Christian Harris
Christian is an experienced swing trader with years actively trading stocks, futures, forex, and cryptocurrencies. He focuses on short- to medium-term strategies, combining technical analysis with disciplined risk management. His real-world trading experience helps him provide valuable perspectives for aspiring swing traders.
Contributor Image
Edited By
Contributor Image
Edited By
James Barra
James is an investment writer with a strong focus on evaluating swing trading platforms. Drawing on his background in financial services, he brings a clear, analytical perspective. He researches, writes, edits, and fact-checks content across several online trading websites, with an emphasis on broker reviews and educational resources designed for swing traders.
Contributor Image
Fact Checked By
Contributor Image
Fact Checked By
Tobias Robinson
Tobias brings over 25 years of hands-on trading experience across stocks, futures, commodities, bonds, and options. He leads the testing team at SwingTrading.com, focusing on broker reviews and trading tools tailored to the needs of active swing traders.
Updated

With spreads eating into profits, fixed-spread brokers offer consistency and clarity, helping traders better manage costs and strategies. But not every fixed spread broker is created equal.

We’ve highlighted the best swing trading brokers with fixed spreads so you can trade confidently, without worrying about hidden surprises.

How SwingTrading.com Chose The Top Fixed Spread Trading Accounts

We identified the best brokers for fixed spreads by reviewing spread levels across major instruments, checking for hidden fees or trading restrictions, and testing execution in both normal and volatile market conditions.

By blending these data points with our own trading experience, we highlighted brokers that genuinely deliver stable, cost-effective fixed spreads rather than marketing them with caveats.

What Are Fixed Spreads?

Fixed spreads remain unchanged whether you’re holding through calm sessions, volatile news releases, or overnight rollovers.

For example, a broker might offer a fixed spread of 1.0 pip on GBP/USD or 2.0 pips on EUR/JPY—and that cost won’t fluctuate, even if spreads on variable accounts widen to 5.0 or 10 pips during low-liquidity hours.

For example, suppose you’re holding a GBP/USD swing trade over the weekend. In that case, a fixed spread account keeps your costs predictable at 1.0 pip.

In contrast, a variable account could suddenly widen several pips at the Sunday open, eating into your carefully calculated risk-reward.

This predictability is valuable for swing traders, since positions often span multiple sessions and weekends, when markets can gap and variable spreads can spike.

While fixed spreads are usually a touch higher on average, they insulate you from overnight surprises—making it easier to plan trades, calculate risk-reward ratios, and stick to a disciplined strategy.

Through years of swing trading, I’ve found that reliable fixed spreads aren’t just about lower costs—they give me confidence that stop-losses and take-profits execute as planned, even during market turbulence.

That certainty lets me focus on strategy, not unexpected trading fees.

author image
Christian Harris
Author

Do All Brokers Offer Fixed Spreads?

Not all brokers offer fixed spreads, and those that do rarely apply them across every instrument.

Typically, fixed spreads are limited to the most liquid majors—such as 1.5 pips on USD/JPY or 3.0 pips on GBP/CHF—while more volatile or exotic pairs, indices, and commodities are left on variable pricing.

This is because maintaining a fixed spread on thinly traded markets would expose the broker to excessive risk. That means while you may enjoy predictable costs on your core forex setups, positions in cross pairs or commodities like gold often come with variable spreads that can widen significantly during rollovers or weekend gaps.

Fixed spreads at easyMarkets

easyMarkets’ fixed spreads never change—no matter how volatile markets are

Trade Illustration: Fixed vs Variable Spreads

To see how fixed and variable spreads affect real trading outcomes, let’s look at a short-term trade on Gold (XAU/USD).

This scenario compares the same trade under both pricing models, showing how the spread impacts net profit depending on market conditions.

Trade Setup:

  • Position: Buy 1 lot of Gold (equivalent to $100 per $1 movement)
  • Entry price: $3,000
  • Exit price: $3,010
  • Market movement: +$10 in your favour

Scenario 1: Fixed Spread Broker

  • Fixed spread: 20 pips ($2)
  • Effective entry price: $3,002
  • Exit price: $3,010
  • Net gain: $8
  • Profit: $800

Scenario 2: Variable Spread Broker (Normal Market Conditions)

  • Variable spread: 10 pips ($1)
  • Effective entry price: $3,001
  • Exit price: $3,010
  • Net gain: $9
  • Profit: $900

Scenario 3: Variable Spread Broker (During Volatility)

  • Variable spread: 50 pips ($5)
  • Effective entry price: $3,005
  • Exit price: $3,010
  • Net gain: $5
  • Profit: $500

In calm market conditions, variable spreads can offer slightly better profitability, as the cost per trade is lower.

However, during high-volatility periods—such as major economic announcements or thin trading hours—variable spreads can widen dramatically.

Fixed spreads provide cost certainty in these moments, helping you maintain planned risk-reward ratios and protect trades from unexpected slippage.

Pros Of Fixed Spreads

  • Cost predictability across multi-day holds: With fixed spreads, a pair like EUR/USD at 2.0 pips stays the same whether you hold for a few hours or several days. For swing traders who often ride positions through multiple sessions, this removes the uncertainty of spread widening during overnight rollovers, weekend gaps, or low-liquidity Asian hours. It makes forward risk-reward calculations more reliable.
  • Protection against volatility-driven spread spikes: News events, thin liquidity, or market opens can push variable spreads from 0.5 pips to 8+ pips in seconds. Fixed spreads insulate you from these unexpected costs, ensuring that a carefully placed stop-loss isn’t eaten up by sudden, artificial spread widening rather than genuine price movement.
  • Stable backtesting & strategy execution: Swing traders often rely on historical testing of risk-reward ratios, where consistent entry/exit costs matter. With fixed spreads, transaction costs are easier to model in backtests and apply in live trading. This consistency reduces slippage between theory and practice, especially on longer-term setups that don’t rely on ultra-tight scalping spreads.

Cons Of Fixed Spreads

  • Generally wider than variable spreads in calm markets: Fixed spreads are often set slightly higher to account for potential volatility. For example, a fixed GBP/USD spread of 1.2 pips might be wider than a variable spread that could tighten to 0.3–0.5 pips in normal conditions. Over many trades, this can slightly erode profits compared with a broker offering ultra-tight variable spreads.
  • Limited availability across instruments: Fixed spreads are typically offered only on major forex pairs like EUR/USD or USD/JPY, while minors, exotics, commodities, and indices often remain on variable spreads. Swing traders looking to diversify beyond major currencies may still face unpredictable costs on these assets.
  • Potential for reduced market transparency: Fixed spreads are usually provided by market maker brokers, which take the other side of your trade. While the spread stays constant, the broker may adjust pricing internally or apply different fees to manage risk. This can make it harder to know the ‘true’ market cost, especially on larger positions or during volatile periods.

Fixed spreads give me clarity in chart analysis. Knowing the exact spread removes guesswork from entry and exit signals, letting me make cleaner, more precise decisions based purely on price action.
author image
Christian Harris
Author

Bottom Line

Fixed spreads offer swing traders predictability and cost consistency, making it easier to manage multi-day trades and protect positions from sudden volatility or overnight gaps.

While they are typically slightly wider than variable spreads and may be limited to major currency pairs, the stability they provide can simplify risk management and strategy execution.

Choosing the best swing trading broker with fixed spreads ensures that you can focus on your setups rather than worrying about unexpected trading costs.